
ACA & Mental Health: Marketplace Changes Explained
- The number of people enrolled in the Health Insurance Marketplace has more than doubled in recent years, climbing from 11.4 million in 2020 to 24.3 million in 2025,...
- However, proposed policy shifts, including the One Big stunning Bill Act (OBBBA) and the possible expiration of enhanced premium tax credits, could result in 8.2 million people losing...
- Data indicates that one in five Marketplace enrollees report their mental health as "fair" or "poor," according to a KFF survey.
Marketplace Enrollment & Mental Health Care Access Concerns
The number of people enrolled in the Health Insurance Marketplace has more than doubled in recent years, climbing from 11.4 million in 2020 to 24.3 million in 2025, according to KFF data. Access to insurance is crucial for obtaining health care services,including mental health support.
However, proposed policy shifts, including the One Big stunning Bill Act (OBBBA) and the possible expiration of enhanced premium tax credits, could result in 8.2 million people losing their Marketplace coverage by 2034, the Congressional Budget Office (CBO) projects. This potential loss of coverage raises important concerns about access to mental health services.
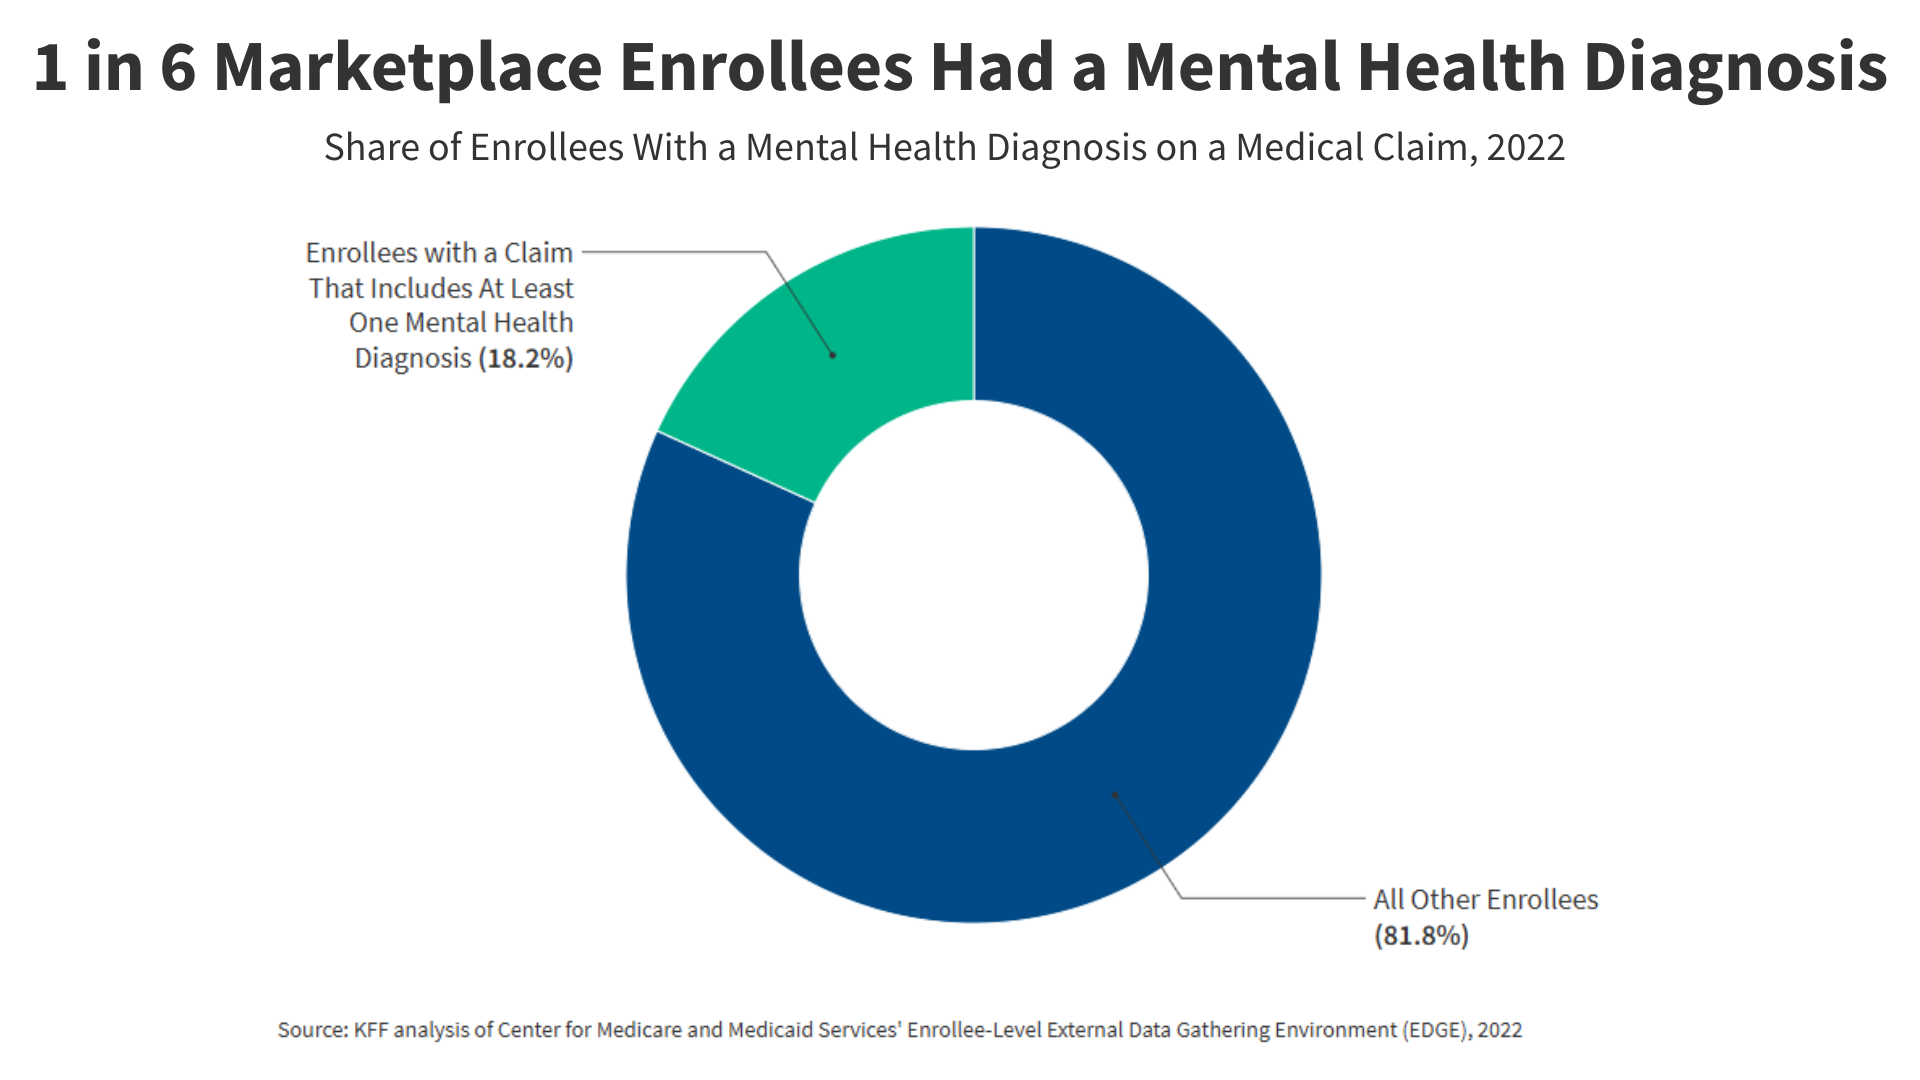
Data indicates that one in five Marketplace enrollees report their mental health as “fair” or “poor,” according to a KFF survey. An estimated 18.2%, or over 4.4 million, Marketplace enrollees had at least one mental health diagnosis on a health care claim in 2022, according to data from the Center for Medicare and Medicaid Services. This figure likely understates the true prevalence, as it only captures diagnosed individuals with recorded medical claims.
Among Marketplace enrollees with a mental health diagnosis, anxiety disorders were the most common (3.0 million), followed by depression disorders (2.0 million), trauma and stressor-related disorders (0.9 million), and bipolar disorders (0.3 million). Mental health conditions frequently enough co-occur,with 39% of enrollees having claims that include two or more diagnoses.
mental health diagnoses were most prevalent among adults ages 26-34 and among female enrollees. women were more likely than men to have a mental health diagnosis on a health care claim (22.8% vs. 12.8%).
The Affordable Care Act (ACA) has improved access to mental health and substance use services through essential health benefits, coverage for pre-existing conditions, and parity protections. Record enrollment, driven by enhanced premium tax credits and simplified sign-up processes, has further expanded access. However, pending policy changes could reverse these gains.
If enrollees with mental health conditions lose coverage at a similar rate to others, over one million more people with a mental health diagnosis could become uninsured by 2034. Separate CBO estimates suggest that changes to Medicaid through the OBBBA could further increase the number of uninsured by 7.8 million. Medicaid plays a significant role in behavioral health coverage, supporting nearly one-third of adults with mental health disorders.
Insured individuals with anxiety or depression are significantly more likely to receive mental health care than their uninsured counterparts (64% vs. 38% in 2019). Loss of insurance coverage would exacerbate the financial burden of seeking mental health treatment, as healthcare expenditures for those with mental health conditions are typically higher.
A 2023 KFF survey revealed that 43% of insured adults with ”fair” or “poor” mental health reported forgoing needed mental health care due to cost concerns. Maintaining access to affordable insurance is thus critical for ensuring access to mental health services.