
Born Digital Research Group Proposes Digital Transformation of Personal Income Reporting
- Tax software vendor freee announced that the Born Digital research group, operating under the Software Association of Japan, released two documents outlining a digital-first framework for personal income...
- The newly published documents include a primary policy proposal titled Digitalization Proposal for New Approaches to Personal Income Reporting and a supporting investigation report examining tax digital transformation...
- Japan's current income reporting mechanisms, such as year-end tax adjustments and final tax returns, rely heavily on paper records processed once a year.
Tax software vendor freee announced that the Born Digital research group, operating under the Software Association of Japan, released two documents outlining a digital-first framework for personal income reporting.
The newly published documents include a primary policy proposal titled Digitalization Proposal for New Approaches to Personal Income Reporting and a supporting investigation report examining tax digital transformation in the United Kingdom. Eight software vendors participate in the research group through individual employee contributions, including Mika Koizumi, executive officer Chief of Public Affairs at freee.
Japan’s current income reporting mechanisms, such as year-end tax adjustments and final tax returns, rely heavily on paper records processed once a year. While electronic filing and administrative APIs have digitized specific document formats, the underlying business processes still operate without a fully digital foundation.
Administrative Costs of Traditional Year-End Adjustments
Year-end adjustments place a heavy operational burden on corporate accounting and human resources departments during the busiest season of the year. Research group estimates place the direct personnel cost for private businesses managing year-end adjustments at between 94 billion and 292 billion yen annually across society.
The proposal suggests treating personal income data as an interconnected information chain rather than separating year-end adjustments, final tax returns, salary payment reports, resident taxes, social insurance, and benefits into isolated administrative silos. Implementing these changes requires close collaboration between government agencies, business operators, experts, and software vendors to advance reforms in practical, incremental stages.
Proposed Structural Reforms for Business and Freelancers
The advisory panel outlines three core areas for reducing administrative friction and modernizing tax collection. First, the group proposes streamlining year-end adjustments to function closer to a simplified version of final tax returns, alongside transitioning salary payment reporting to a real-time framework based on daily payroll calculations.
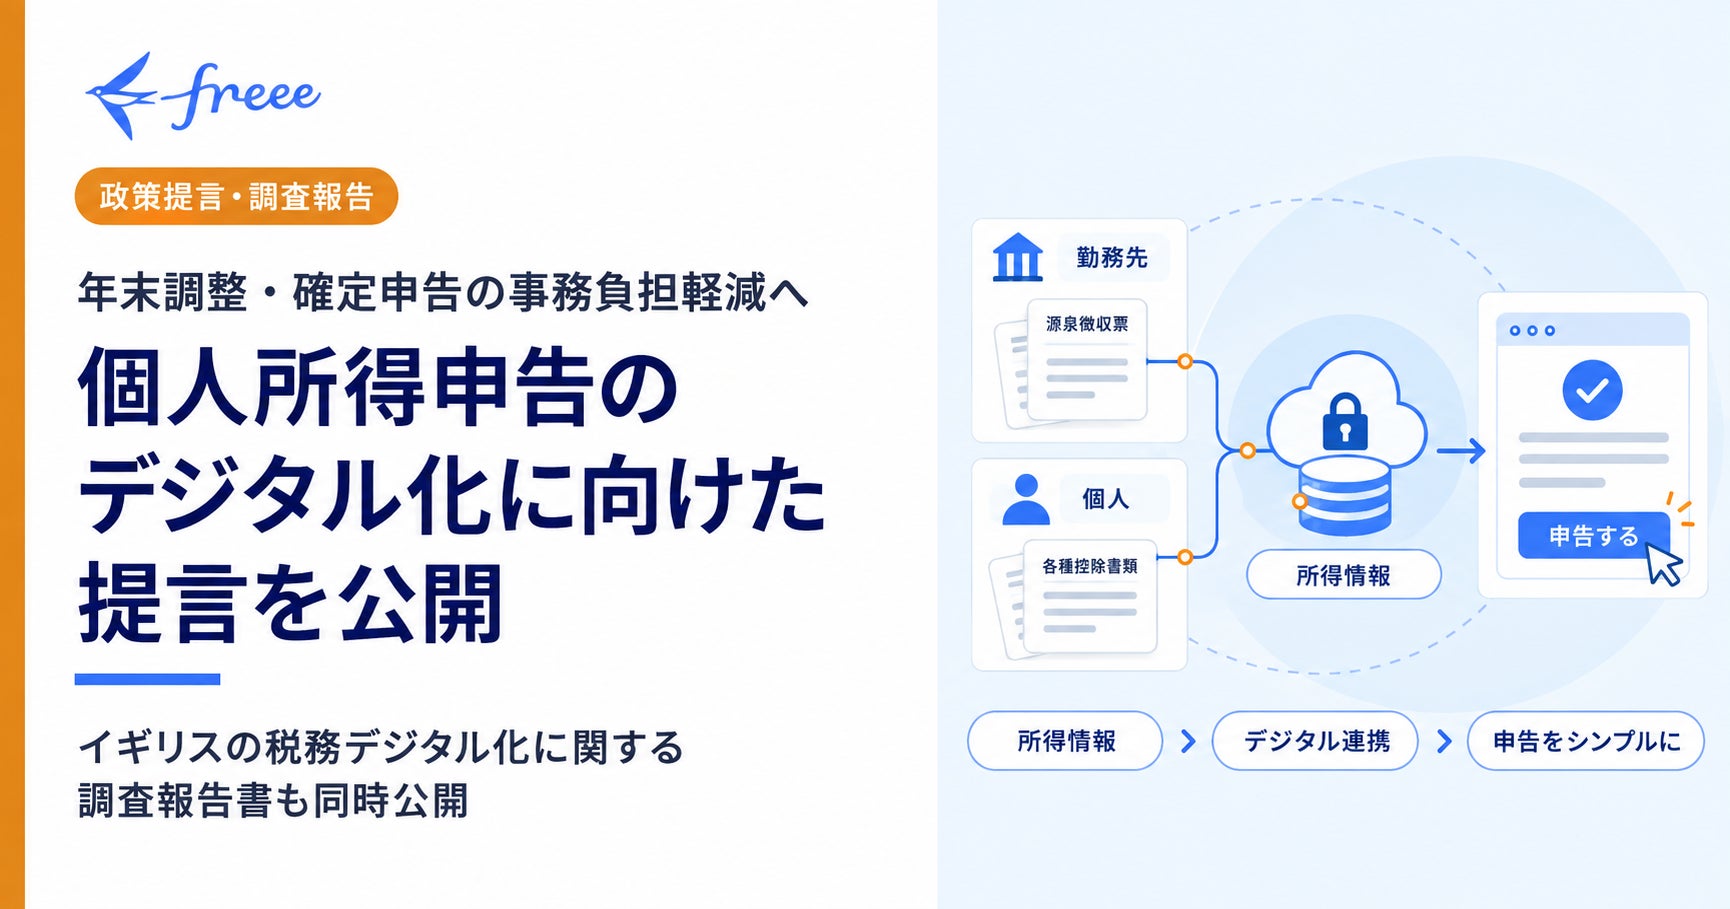
Second, the framework calls for a personal income information infrastructure that allows individuals to check their earnings and deductions securely. This setup aims to enable one-click final tax returns in the future while implementing strict role-based access controls and statutory audit mechanisms to protect sensitive financial data.
Third, the report examines options for simplifying tax compliance for freelancers and side-business workers. Proposed measures include connecting platform transaction data directly to accounting and filing software via APIs and enabling minor transactions to be settled directly through digital platforms.
Lessons from the United Kingdom Tax Digitalization Process
To inform the Japanese proposals, the research group conducted field interviews in the United Kingdom to study its digital tax initiatives. The UK experience highlights the necessity of a clear roadmap and early co-creation between government, software vendors, and tax or accounting professionals.
The UK implemented Real Time Information to collect frequent payroll data without disrupting established business routines, which later supported benefit distribution systems like Universal Credit. Meanwhile, the Making Tax Digital initiative demonstrated that the scale of procedural changes and additional costs directly influences whether digital mandates gain acceptance among taxpayers.
Keep reading