
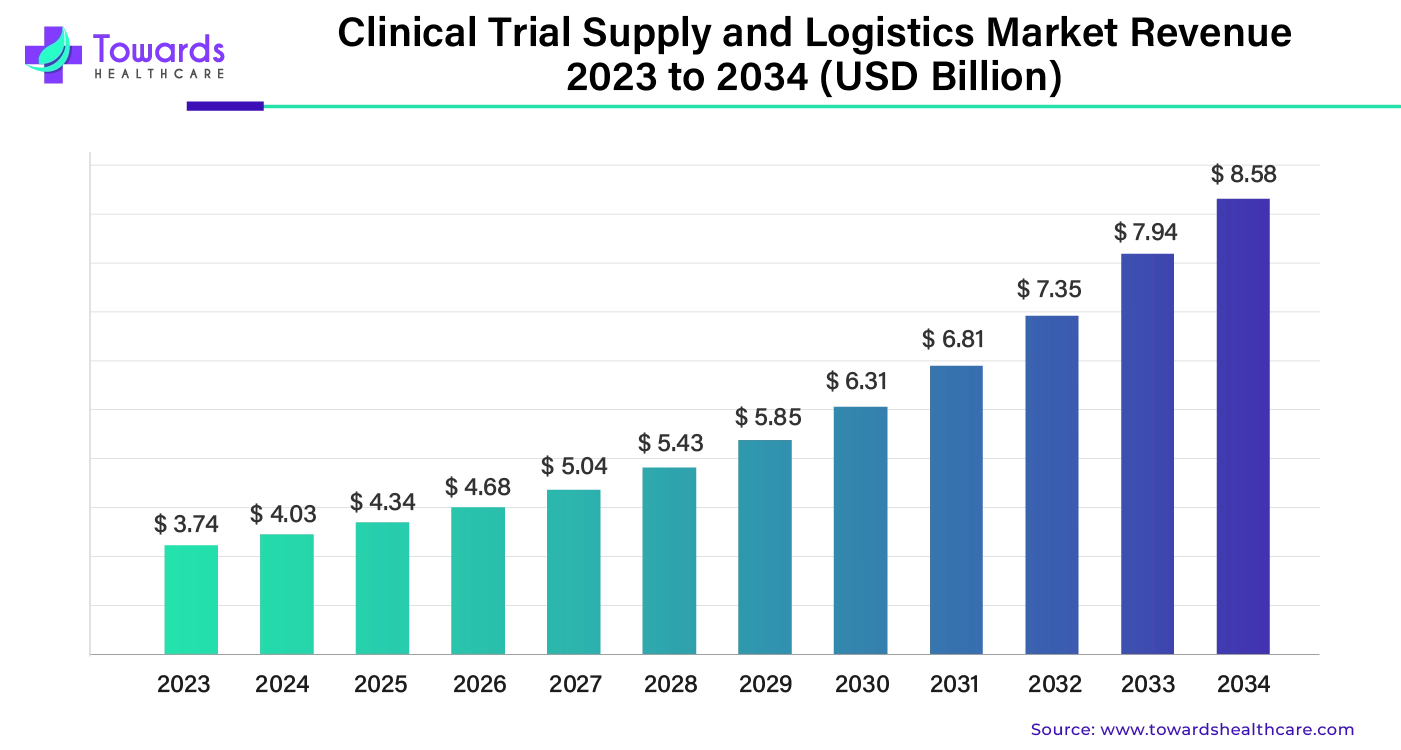
Clinical Trial Supply and Logistics Market Growth: Expected to Reach $7.94 Billion by 2033
- The clinical trial supply and logistics market was valued at USD 4.03 billion in 2024.
- Technological Advancements: The integration of AI and blockchain in logistics management enhances efficiency in the supply chain.
- Decentralized Clinical Trials (DCTs): DCTs have gained popularity due to the COVID-19 pandemic, allowing remote patient participation and reducing the need for site visits.
Clinical Trial Supply and Logistics Market Overview
The clinical trial supply and logistics market was valued at USD 4.03 billion in 2024. It is projected to grow to approximately USD 7.94 billion by 2033, according to a study by Towards Healthcare. This market involves sourcing, packaging, storing, and distributing biopharmaceutical products for clinical trials, including managing drugs, equipment, and data.
Market Drivers
-
Technological Advancements: The integration of AI and blockchain in logistics management enhances efficiency in the supply chain. Real-time tracking and data integrity through blockchain are gaining traction.
- Increase in Clinical Trials: The number of clinical trials has risen, contributing to market growth. In 2021, there were 2,784 phase I clinical drug trials initiated, marking an increase from 2,306 in 2020.
Key Trends
-
Decentralized Clinical Trials (DCTs): DCTs have gained popularity due to the COVID-19 pandemic, allowing remote patient participation and reducing the need for site visits. Their usage increased by 14% in phase I trials from 2021 to 2022.
-
Advanced Technologies: Approximately 45% of clinical logistics providers have adopted Internet of Things (IoT) devices. The usage of blockchain in clinical trials rose by 20% from 2022 to 2024.
- Personalized Treatment Focus: There is a growing interest in patient-centric approaches, with personalized medicines like CAR-T and gene therapy requiring advanced logistics strategies.
Regional Insights
-
North America: The largest share of the market is in North America, attributed to strong healthcare infrastructure and significant investment in clinical trials. The U.S. leads with over 14,000 ongoing clinical trials as of 2023.
- Asia Pacific: This region is expected to show the fastest growth rate due to China’s diverse patient population and India’s rise in phase III trials. Government initiatives to improve healthcare infrastructure also support market expansion.
Market Segmentation
-
By Service: Logistics and distribution represent the largest segment. There is a shift towards temperature-sensitive transport and decentralized trial delivery models.
-
By Phase: Phase III trials lead the market, accounting for 40% of clinical trial budgets worldwide.
- By Therapeutic Area: The cardiovascular disorders segment dominates, reflecting growing drug development in response to rising prevalence.
Competitive Landscape
Some notable companies in this market include Almac Group, FedEx, and Thermo Fisher Scientific. Key areas of focus for these players are end-to-end supply chain management, temperature-sensitive logistics, and decentralized trial support.
Recent Development
FedEx launched the ‘FedEx Life Science Center’ in Mumbai in February 2024, marking a significant advancement in clinical trial logistics.
The clinical trial supply and logistics market is evolving rapidly, driven by technology, increasing trials, and a focus on personalized medicine.