
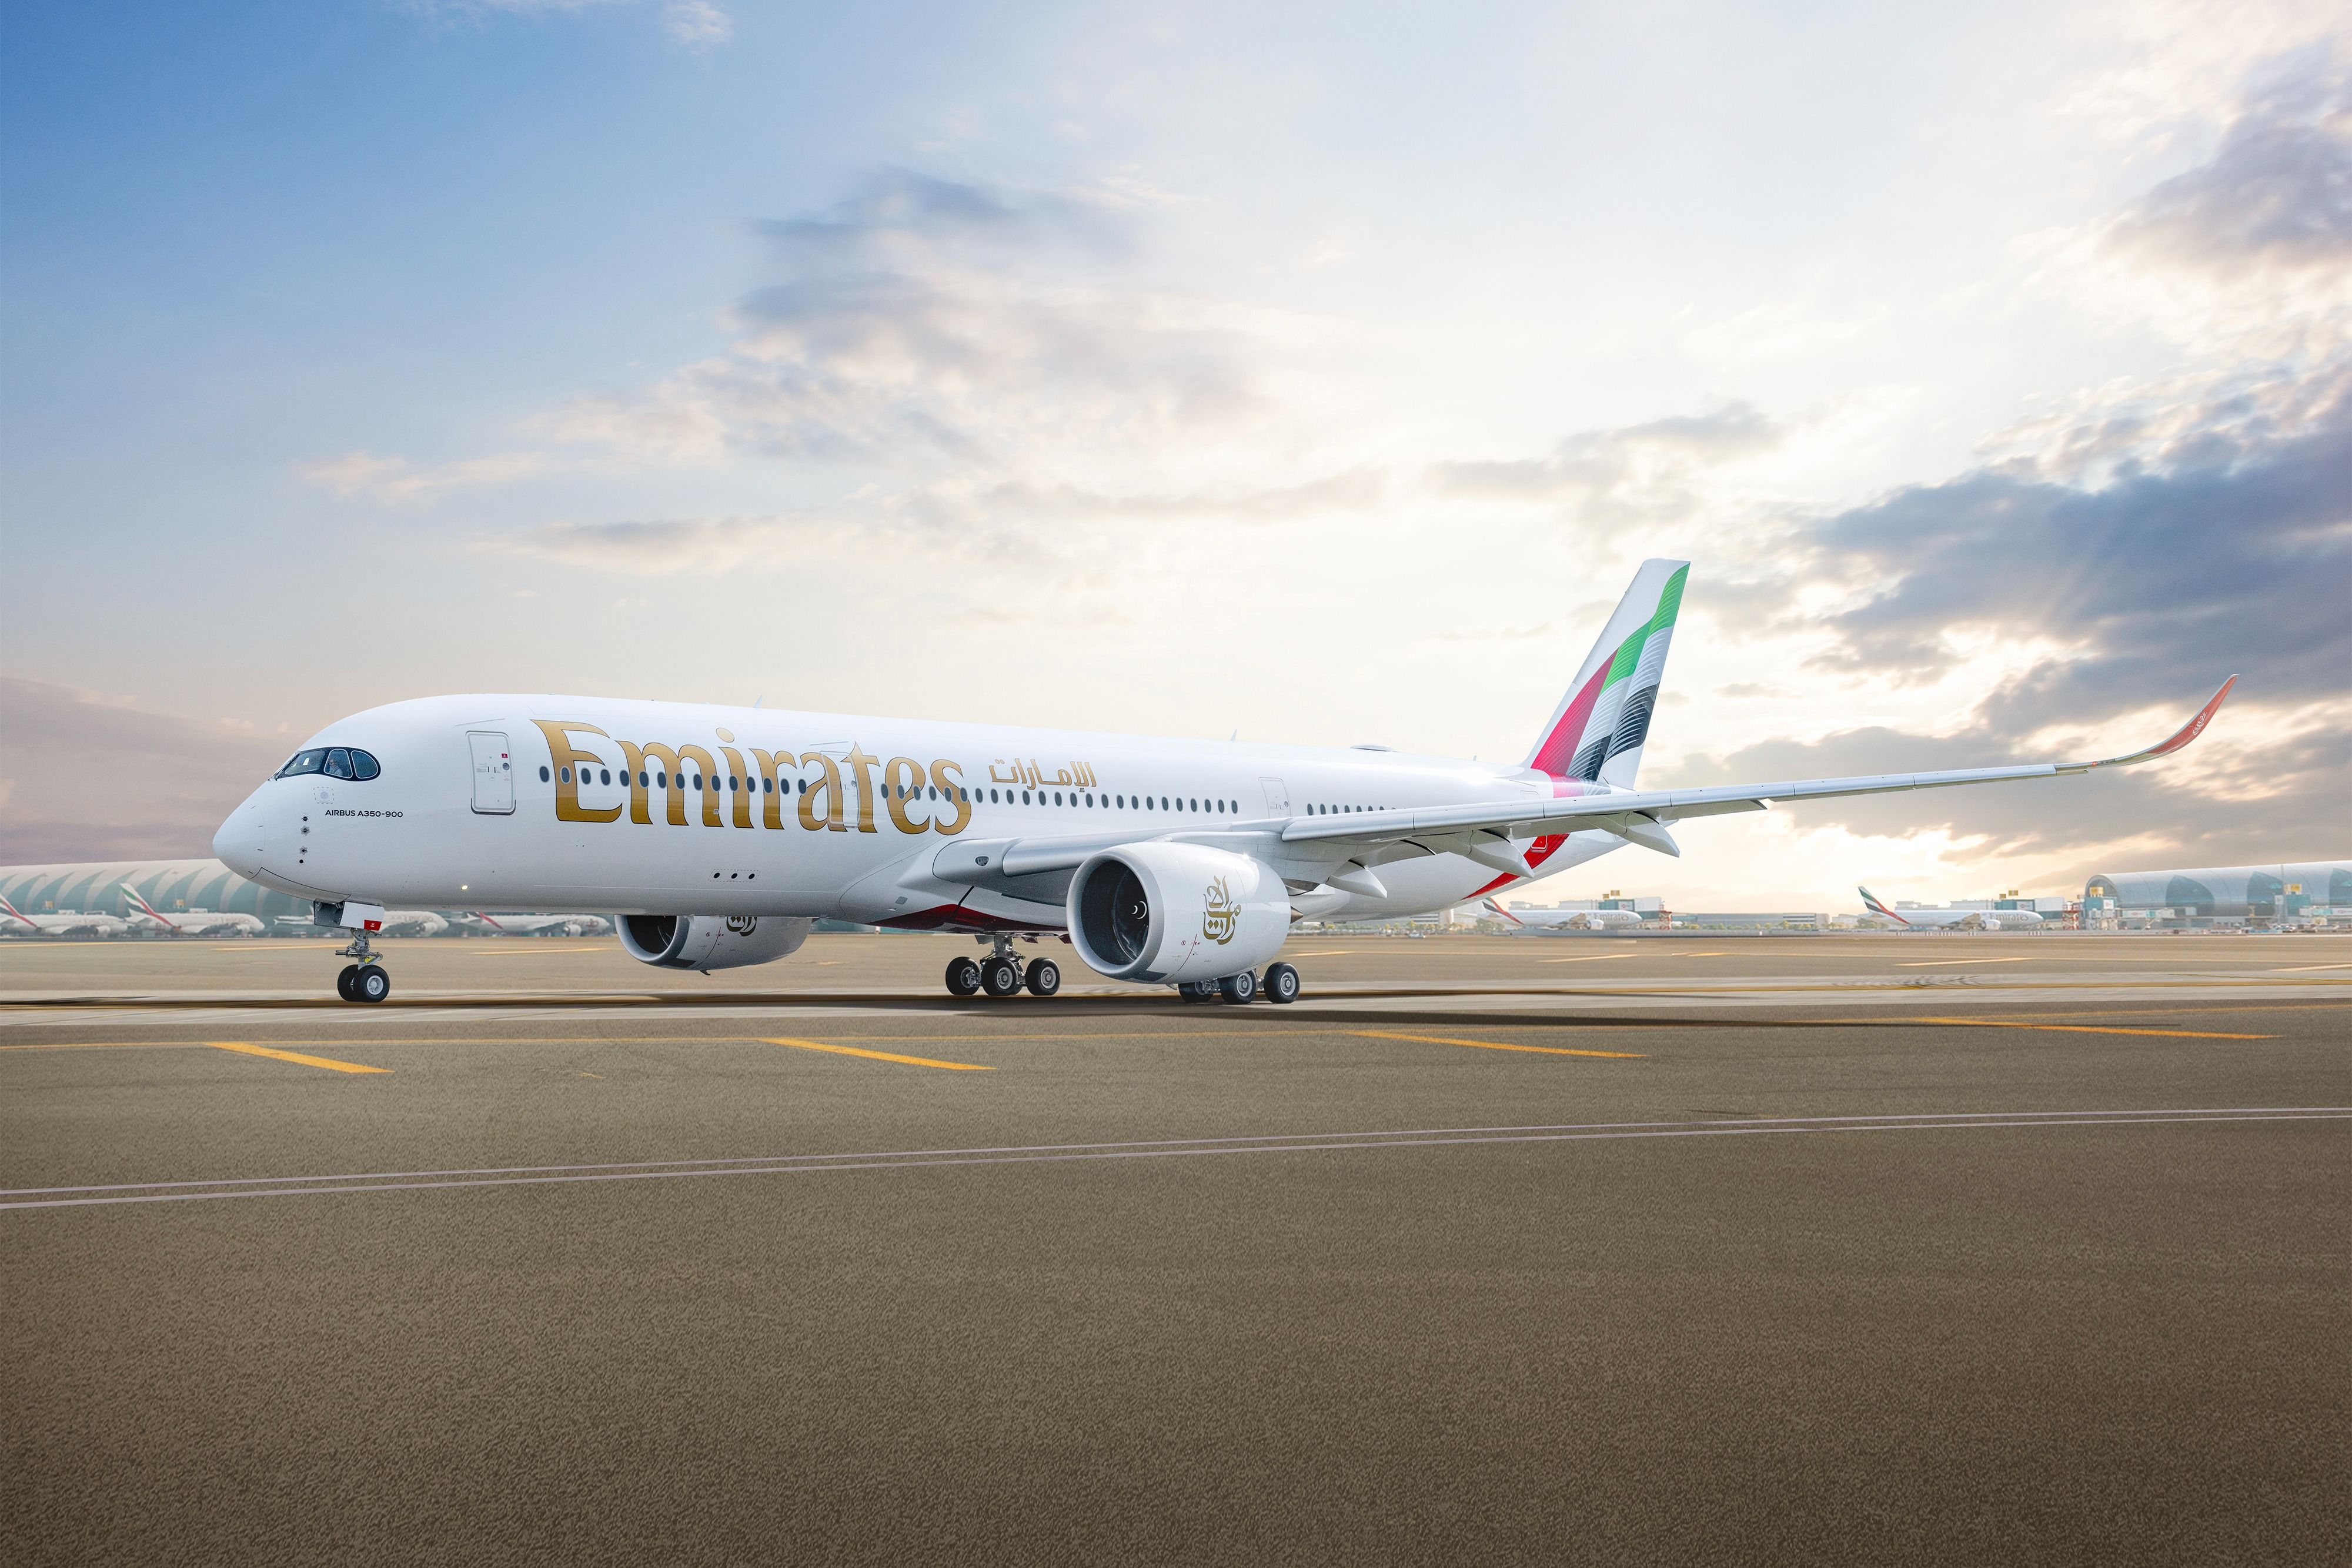
Emirates Faces Highest Aviation Carbon Costs Due to Long-Haul Flight Dominance, MSCI Warns
- Emirates faces potential $127 billion industry-wide carbon cost surge as long-haul reliance exposes airlines to credit market strain, according to MSCI Carbon Markets.
- The airline industry could incur up to $127 billion in additional costs by 2030 due to a global carbon credit shortage, with Emirates among the most exposed carriers,...
- Emirates operates the world’s largest long-haul fleet by passenger capacity, with routes averaging 8,000+ kilometers per flight—nearly double the industry average.
Emirates faces potential $127 billion industry-wide carbon cost surge as long-haul reliance exposes airlines to credit market strain, according to MSCI Carbon Markets. The Dubai-based carrier, which operates one of the world’s largest long-haul networks, could be among the hardest hit by a projected 20%–30% shortfall in carbon credit availability by 2030, forcing carriers to pay premium prices or cut routes.
The airline industry could incur up to $127 billion in additional costs by 2030 due to a global carbon credit shortage, with Emirates among the most exposed carriers, MSCI Carbon Markets said in a report released June 28. The firm’s analysis projects that long-haul operators—particularly those reliant on older aircraft fleets—will face the steepest financial impact as credit prices surge beyond current market forecasts.
Why is Emirates uniquely vulnerable?
Emirates operates the world’s largest long-haul fleet by passenger capacity, with routes averaging 8,000+ kilometers per flight—nearly double the industry average. According to the International Air Transport Association (IATA), long-haul flights account for 40% of Emirates’ total emissions, yet only 15% of its revenue. This structural mismatch means carbon costs will hit profitability harder than for short-haul competitors.
MSCI’s data shows that Emirates’ carbon exposure could reach $5.2 billion annually by 2030 if current credit supply trends persist, assuming a $150/tonne carbon price—up from the $85/tonne average in 2025. For context, this represents 12% of Emirates’ 2024 pre-tax profit of $4.3 billion, according to its latest annual filing.
How does this compare to other airlines?
While all major carriers face rising carbon costs, Emirates’ exposure stands out due to three factors:
- Route structure: Long-haul flights emit 2.5x more CO₂ per passenger than short-haul trips, per IATA’s 2023 emissions report.
- Fleet age: Emirates’ average aircraft age is 11.3 years, older than competitors like Qatar Airways (8.9 years) or Singapore Airlines (9.5 years). Older planes are less fuel-efficient, increasing carbon liability.
- Market position: As the world’s largest international airline by revenue (excluding alliances), Emirates has no domestic market to offset—unlike European carriers, which can leverage EU Emissions Trading System (EU ETS) compliance credits.
By contrast, Delta Air Lines—whose network is 60% domestic—faces lower carbon costs relative to revenue, MSCI estimates. Even Qatar Airways, which operates a younger fleet, could see carbon expenses rise by $2.1 billion annually by 2030, or 8% of its 2024 profit.
What are the immediate financial pressures?
Emirates has already signaled adjustments to mitigate costs. In its May 2026 investor day, the airline confirmed plans to:
- Accelerate fleet modernization, ordering 50 additional Airbus A350s (20% more efficient than current long-haul planes) to replace older Boeing 777s.
- Explore carbon offset partnerships, though MSCI notes these remain voluntary and unregulated, offering limited price stability.
- Review unprofitable long-haul routes, with internal discussions focusing on Australia, South Africa, and parts of Southeast Asia, per a source familiar with the carrier’s strategy.
Yet these measures may not fully offset the credit market strain. "The real risk isn’t just higher costs—it’s the volatility," said a carbon markets analyst at S&P Global Mobility. "If credit supply tightens further, Emirates could face sudden spikes in 2028–2029, forcing route cuts or fare hikes at a time when demand is already slowing in key markets like China."
What happens next for Emirates and the industry?
Three scenarios are emerging for Emirates and peers:

- Credit market stabilization: If new supply enters by 2027 (e.g., from expanded forestry projects or technological carbon removal), prices could plateau. MSCI projects a $120/tonne equilibrium by 2035.
- Regulatory intervention: The International Civil Aviation Organization (ICAO) is under pressure to mandate binding carbon budgets for airlines, which could force Emirates to pre-purchase credits at today’s lower prices.
- Operational overhaul: Carriers may adopt dynamic routing—avoiding high-emission airspace—or hybrid business models, like Emirates’ recent cargo-focused long-haul flights to offset passenger emissions.
For now, Emirates is monitoring developments closely. "We’re engaged with policymakers and carbon market stakeholders to ensure our long-term strategy aligns with global decarbonization goals," a spokesperson told Reuters in June. The airline has not disclosed specific carbon budgets or cost projections beyond 2026.
Key takeaway
Emirates’ carbon exposure underscores a broader industry shift: by 2030, long-haul airlines could pay 3x more for carbon credits than in 2025, reshaping profitability and route networks. While Emirates’ deep pockets and global scale offer some resilience, the carrier’s reliance on high-emission routes makes it a bellwether for the industry’s transition costs.