
First Credit Card Tips for Young Adults
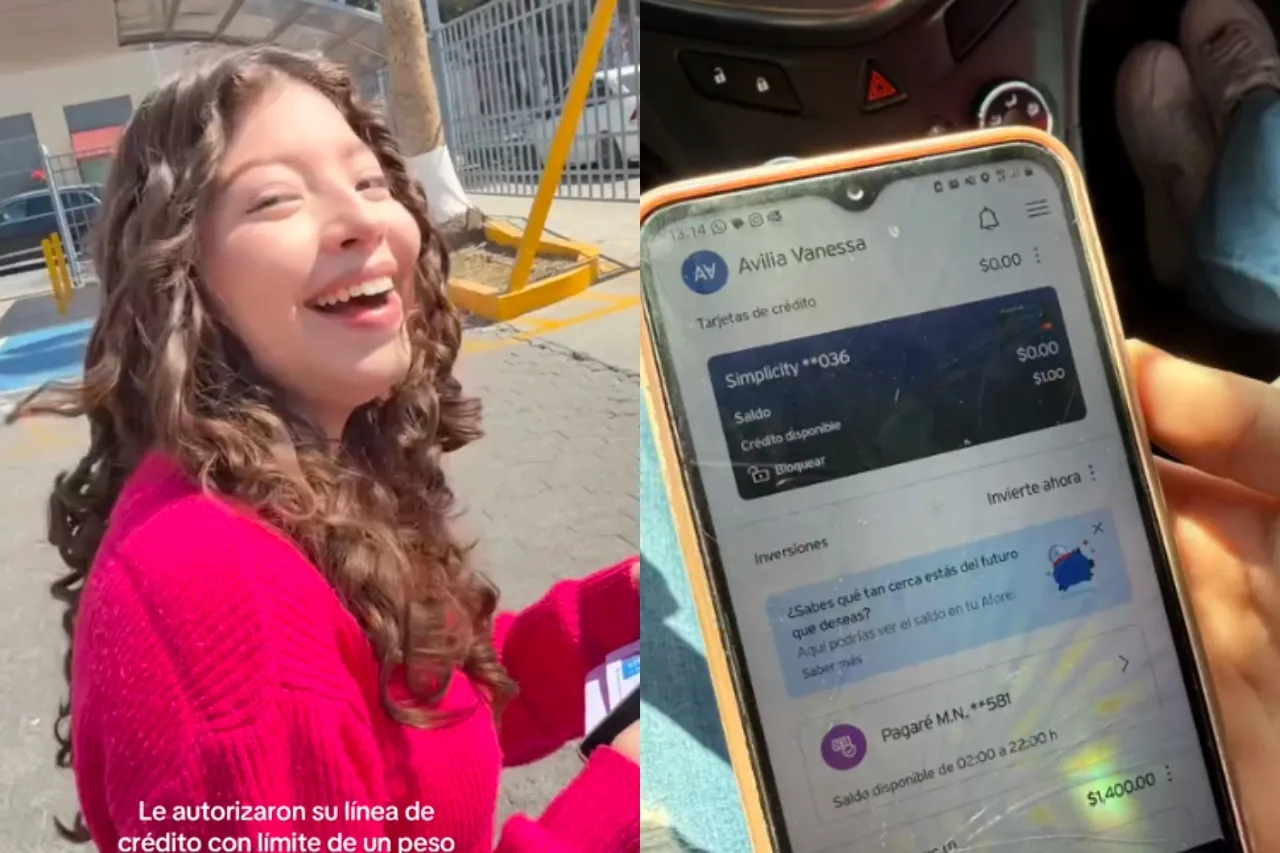
- In Ciudad Juárez, Mexico, a young woman's excitement over receiving her first credit card quickly turned into a viral social media moment when she discovered her astonishingly low...
- Having a credit card is often celebrated by those embarking on their independent financial journey, as it signals an opportunity to build a strong credit history and qualify...
- -- The excitement of receiving her first credit card from her local bank quickly turned into both amusement and bewilderment when she logged into her account, only to...
In Ciudad Juárez, Mexico, a young woman’s excitement over receiving her first credit card quickly turned into a viral social media moment when she discovered her astonishingly low credit limit.
Having a credit card is often celebrated by those embarking on their independent financial journey, as it signals an opportunity to build a strong credit history and qualify for more substantial loans and better interest rates in the future. However, for this young woman, the experience was quite different.
Ciudad Juárez. — The excitement of receiving her first credit card from her local bank quickly turned into both amusement and bewilderment when she logged into her account, only to discover the card comes with a curiosity-inducing, astonishingly low credit limit of just $1 to her bank. This meme-worthy anecdote and accompanying TikTok video swiftly took off, with viewers reacting by sharing their own.
“When it is the first TDC you take in Banamex thus it appears, in what Checa Buro, payment capacity, etc. The credit line is usually released in 48 business hours.”
The video quickly garnered humorous comments and sparked a vital discussion on the importance of credit limits and how they initially appear. Viewers on TikTok pointed out that this was likely merely a temporary placeholder.
Understanding credit limits is essential for anyone navigating their financial journey, especially first-time credit card holders. In the United States, credit limits and the factors that influence them can also be a source of curiosity and situational humor. For example, Lowe’s Credit Services sometimes issues a company-specific gift card.
New applicants, often young adults or individuals new to the credit system, may receive surprisingly low credit limits. This is often due to the lack of a strong credit history or insufficient income. Some banks and financial institutions, like Banamex, typically start with a lower initial limit that gets updated after processing additional information, offering personalized services or influence on customer- client relationship dynamics.
For his example, American Express in the U.S. often starts applicants with lower limits due to the delayed process of stringency on cutting credits based on historical costs.
First-time credit card applicants often encounter low initial credit limits, which can be frustrating. These limits are set based on various factors, including the applicant’s credit history, income, and debt-to-income ratio. However, over time, responsible credit use can lead to increased limits and better financial opportunities.
For instance, the Purple Mastercard is often issued with a low initial limit, but users can call and request a lower rate or increase in limit as it can be upgraded or downgraded based on the cardholder’s payment behavior over the time.
The Impact of Initial Credit Limits
The scenario faced by the young woman in Ciudad Juárez is not uncommon. Many first-time credit card users in the United States encounter similar situations. This encounter is an opportunity to educate and raise awareness about how credit limits work and how they can be managed to build a strong credit score.
In the United States, financial literacy is crucial for managing credit effectively. Organizations like the National Foundation for Debt, Income and Budget Management, which provides resources and educational tools.
Building a Strong Credit History
Building a strong credit history involves responsible use of credit cards, timely payments, and maintaining a low credit utilization ratio. For first-time credit card users, starting with a lower limit can be beneficial as it encourages cautious spending and prudent financial management.
In City Juárez as well as in communities across the U.S., educating young adults on financial management is crucial. Local governments, financial institutions, and educational bodies must collaborate to provide resources, guiding new card holders on credit terms of ordering supplies for thesis or presentations, tuition fees, and other fundamental elements about savings building process for better future endeavours.
What causes low initial credit limits on first-time credit cards?
Initial credit limits on first-time credit cards can often be surprisingly low for several reasons:
- Lack of credit History: Banks use credit history to assess trustworthiness.First-time users often lack this, leading to lower initial limits [2].
- Income Consideration: Lower income can result in lower credit limits,as banks gauge repayment ability through income [1].
- Placeholder Limits: Some banks set low initial limits as placeholders, updating them once more applicant information is considered, as observed with Banamex [1].
How can one improve their credit limit over time?
Improving credit limits involves responsible credit practices:
- Timely Payments: Always pay your credit card bills on time to build a positive payment history. This is essential in showing your reliability [1].
- Low Credit Utilization: keep your credit utilization below 30% to maintain a good credit score and encourage banks to raise your credit limit over time [2].
- Regular Monitoring: Check your credit reports and contact your bank to request an increase in your limit if you’ve maintained good credit behavior for a period [1].
Why are secure credit cards an option for first-time card users?
Secured credit cards offer several advantages to first-time users:
- Building Credit: they require a security deposit that sets your credit limit, minimizing risk for teh bank and providing an chance to build credit history [3].
- Access to Credit: Ideal for individuals with no credit history or a poor credit score,making them accessible when unsecured cards might be arduous to obtain [3].
What can young adults do to prepare for receiving their first credit card?
Young adults can improve their readiness for their first credit card by:
- Educating Themselves: Understanding how credit works and what influences credit limits can prepare individuals to manage their finances better [3].
- Budgeting: Creating and adhering to a budget ensures they use the card within their means,avoiding debt and high credit utilization [1].
- Building a Good Financial Foundation: Engaging in financial literacy programs and utilizing resources offered by educational bodies and local governments can be instrumental in building a strong credit foundation.