
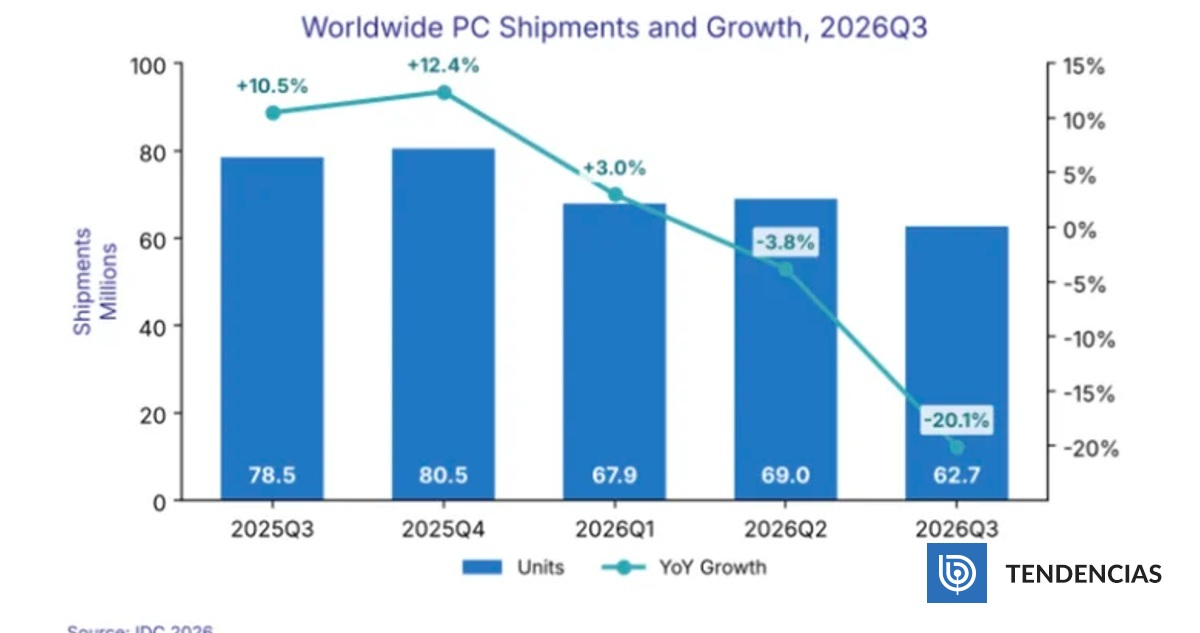
Global PC Shipments Drop 20.1 Percent in Third Quarter of 2026
- Global personal computer shipments fell 20.1% year-over-year during the third quarter of 2026, reaching 62.7 million units, compared to the 78.5 million units shipped in the same period...
- While both major consultancy firms point to a sharp market cooling, their exact shipment figures differ slightly due to methodological variations.
- Jitesh Ubrani, research director for consumer devices at IDC, explained that much of the drop stems from manufacturers and sales channels stocking up early in the year to...
Global personal computer shipments fell 20.1% year-over-year during the third quarter of 2026, reaching 62.7 million units, compared to the 78.5 million units shipped in the same period of 2025, according to data from market research firm IDC. BioBioChile reported that the drop marks the worst slump for the industry since early 2023, contrasting sharply with the second quarter and defying normal seasonal patterns where third-quarter sales typically outpace the previous period.
Diverging Estimates From IDC And Omdia
While both major consultancy firms point to a sharp market cooling, their exact shipment figures differ slightly due to methodological variations. IDC recorded total shipments of 62.7 million units, representing a 20.1% annual drop from the 78.5 million units shipped in the third quarter of 2025, alongside a 9.1% decline compared to the 68.2 million units shipped in the second quarter of 2026. Omdia measured an even steeper annual decline of 21.2%, bringing total shipments down to 58.1 million units. Within Omdia’s breakdown, desktop computers and workstations fell 23.5% to 11.7 million units, while laptops dropped 20.6% to 46.4 million units.
The Impact Of Early Stockpiling And Artificial Intelligence
Jitesh Ubrani, research director for consumer devices at IDC, explained that much of the drop stems from manufacturers and sales channels stocking up early in the year to get ahead of rising component costs. That aggressive early purchasing inflated the numbers for the first half of 2026 and left very little residual demand for the third quarter. Behind those higher costs lies an ongoing shift driven by artificial intelligence. Ben Yeh, principal analyst at Omdia, noted that the intense appetite for specialized hardware—such as high-bandwidth memory (HBM) for AI chips and server-grade DRAM—has monopolized factory capacity. As a result, consumer devices face tighter supplies and surging prices. Si miramos todos los trimestres, hemos visto otros con caídas mayores en los últimos años, como el cuarto trimestre de 2022, con -28,2%, y el primero de 2023, con -28,7%,
said Jitesh Ubrani.

Surging Component Costs And Manufacturer Pressures
Component pricing shifts have drastically altered hardware economics. Omdia reported that DRAM memory and solid-state drives now account for roughly 40% of a PC’s total material costs, compared to the traditional 15%. Infobae noted that DRAM prices reached $25 in August—marking a 4.4-fold increase over the prior year—while NAND flash memory climbed to $30.50, nearly nine times its value from twelve months earlier. Yeh stated that overall computer prices have surged more than four times over their previous values. Among major hardware makers, HP experienced the steepest drop with a 31% decline to 10.3 million units, while Dell fell 25% to 7.6 million units, and Apple weathered the downturn better with an 11.3% reduction to 6.8 million units, according to Infobae’s reporting.
Projections And Future Market Outlook
Omdia projects further contraction ahead, forecasting a 24% annual drop in shipments for the fourth quarter of 2026 and an additional 7% decline throughout 2027. TrendForce warned that rising central processing unit (CPU) and memory expenses could push next year’s portable computer declines into the high single digits, potentially near 10%. While pinched distributors holding heavy inventories may introduce short-term promotions, IDC cautions that overall prices will remain well above last year’s levels.
Manufacturing Locations And Hardware Pressures
According to TrendForce, the global production of portable computers located outside of China accounted for approximately 24% in 2025. In addition, printed circuit boards, multi-layer ceramic capacitors, and power management integrated circuits also face pressures related to raw materials, capacity allocation, and geopolitical factors. Shifting all cost increases to the buyer can delay equipment upgrades, while absorbing those costs would hurt profit margins.