
Gulf States: Alternatives to the Strait of Hormuz
- The Gulf Cooperation Council (GCC) states are maintaining strategic investments in land-based pipeline infrastructure to mitigate the economic risks associated with the Strait of Hormuz.
- The strategic necessity for these alternatives stems from the persistent threat of maritime disruptions in the Persian Gulf.
- Saudi Arabia possesses the most robust alternative to the Strait via the East-West Pipeline, also known as Petroline.
The Gulf Cooperation Council (GCC) states are maintaining strategic investments in land-based pipeline infrastructure to mitigate the economic risks associated with the Strait of Hormuz. This maritime chokepoint remains the world’s most critical oil transit route, with approximately 21 million barrels of oil and condensate passing through the waterway daily.
The strategic necessity for these alternatives stems from the persistent threat of maritime disruptions in the Persian Gulf. Because the Strait of Hormuz is the only sea exit for oil exports from Iraq, Kuwait, and the United Arab Emirates, as well as liquefied natural gas (LNG) from Qatar, any closure would trigger immediate global energy price volatility.
Saudi Arabia and the East-West Pipeline
Saudi Arabia possesses the most robust alternative to the Strait via the East-West Pipeline, also known as Petroline. This infrastructure allows the kingdom to transport crude oil from its eastern fields to the Red Sea port of Yanbu, completely bypassing the Persian Gulf.
The pipeline system is designed to move millions of barrels per day, providing a critical hedge against regional instability. By diverting flows to the Red Sea, Saudi Arabia can maintain exports to European and North American markets even if the Strait of Hormuz is rendered impassable.
The UAE’s Strategic Pivot to Fujairah
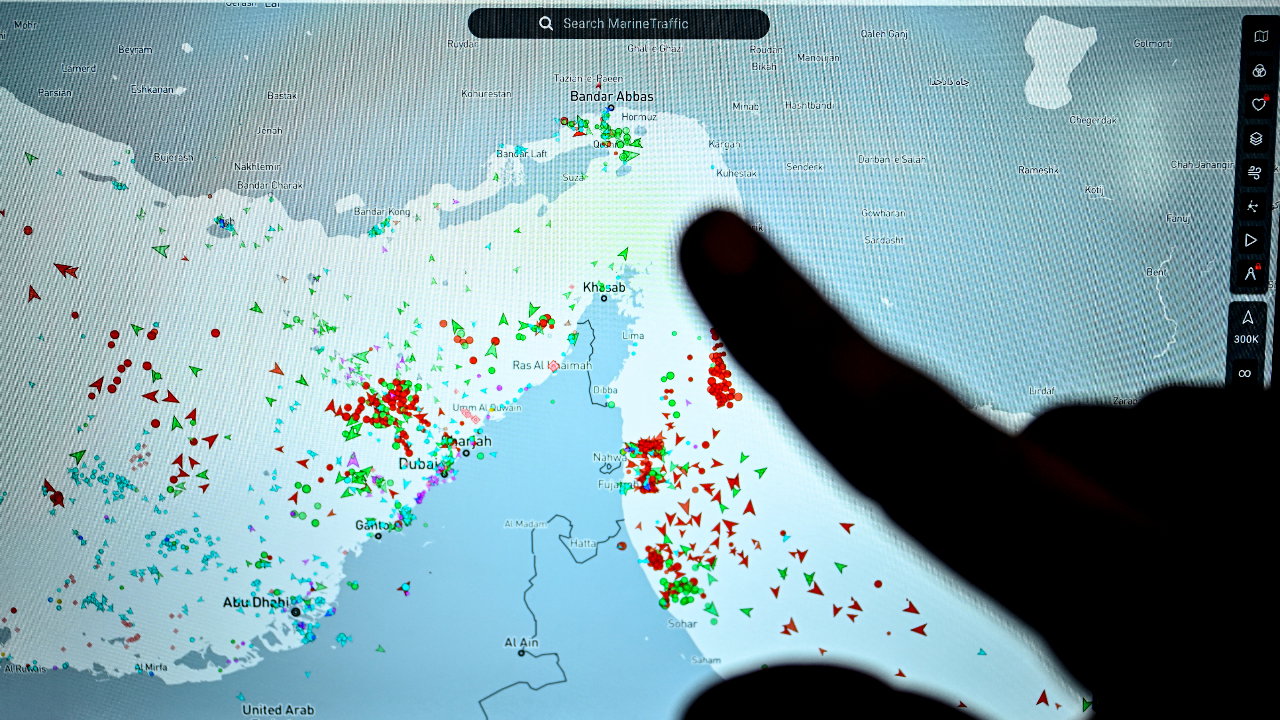
The United Arab Emirates has focused its diversification efforts on the Abu Dhabi Crude Oil Pipeline (ADCOP). This system transports crude from the onshore fields of Abu Dhabi to the port of Fujairah, located on the Gulf of Oman.
Fujairah has evolved into one of the world’s largest bunkering hubs, providing the UAE with a direct gateway to the Indian Ocean. This infrastructure ensures that a significant portion of the UAE’s oil exports can reach global markets without entering the Strait of Hormuz.
While the ADCOP provides a vital safety valve, the total capacity of the pipeline does not cover the entirety of the UAE’s export volume, leaving a portion of its production still dependent on the Persian Gulf’s maritime routes.
Vulnerabilities in Qatar and Kuwait
Unlike Saudi Arabia and the UAE, Qatar and Kuwait face significantly higher levels of exposure to chokepoint risks. Qatar is almost entirely dependent on the Strait of Hormuz for the export of its LNG, which is a cornerstone of its national economy.

Notice currently no large-scale land-based pipeline alternatives capable of transporting the volume of LNG that Qatar produces. Because LNG requires specialized cryogenic shipping and terminals, the infrastructure requirements for a bypass are substantially more complex and costly than those for crude oil.
Kuwait has historically explored pipeline options to move oil to the Mediterranean or the Red Sea, but these projects have faced significant financing and geopolitical hurdles. Kuwait remains heavily reliant on the Strait for its primary export revenue.
Economic and Geopolitical Implications
The development of these bypass routes is not merely a logistical preference but a core component of national security for the Gulf states. The ability to maintain energy flows during a crisis reduces the leverage of any single actor attempting to use the Strait as a geopolitical tool.
However, the reliance on pipelines introduces different risks, including the vulnerability of land-based infrastructure to sabotage or regional conflict. The cost of maintaining and expanding these pipelines is substantial, requiring long-term capital commitments from state-owned energy companies.
As the GCC states continue to diversify their economies away from oil, the strategic importance of these pipelines remains high to ensure that the remaining hydrocarbon revenues are protected from sudden maritime closures.