Homeowners Insurance in Spartanburg: Coverage, Gaps, and Claims Guide
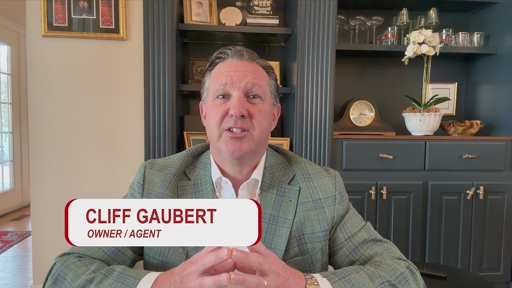
- Homeowners in Spartanburg, South Carolina, face distinct property insurance considerations driven by regional weather risks like strong thunderstorms and hail, according to a HelloNation article featuring insights from...
- When a covered event damages a house structure, standard insurance policies pay for repairs or rebuilding up to the dwelling coverage limit, according to reporting from PRNewswire.
- Beyond the physical structure, standard policies include personal property coverage to reimburse owners if furniture, electronics, appliances, or clothing are stolen or damaged during a covered incident.
Homeowners in Spartanburg, South Carolina, face distinct property insurance considerations driven by regional weather risks like strong thunderstorms and hail, according to a HelloNation article featuring insights from local insurance agent Cliff Gaubert of Cliff Gaubert Ins Agcy Inc. Standard property policies protect against common perils such as fire, wind, lightning, theft, and vandalism, but understanding specific coverage limits and policy gaps remains essential before filing claims.
Understanding Dwelling and Replacement Cost Limits in Spartanburg
When a covered event damages a house structure, standard insurance policies pay for repairs or rebuilding up to the dwelling coverage limit, according to reporting from PRNewswire. Cliff Gaubert notes that these limits should accurately reflect current rebuilding expenses, which often increase over time as construction materials and labor costs rise across Upstate South Carolina. Local weather patterns heavily influence these coverage needs. Because of these persistent local risks, homeowners must review their dwelling coverage regularly to ensure their financial protection keeps pace with market realities.
Personal Property, Liability, and Living Expense Protections
Beyond the physical structure, standard policies include personal property coverage to reimburse owners if furniture, electronics, appliances, or clothing are stolen or damaged during a covered incident. However, high-value items like jewelry, artwork, and collectibles typically carry strict sub-limits unless owners purchase additional policy endorsements, as outlined by PRNewswire. To streamline the claims process, Cliff Gaubert emphasizes the value of maintaining a detailed personal inventory. Keeping recorded item values alongside photos and receipts helps households clearly demonstrate the exact value of lost or damaged possessions. Liability coverage offers another vital layer of financial defense if someone suffers an injury on the property, such as a visitor slipping on a set of steps. This portion of the policy helps cover resulting medical bills and legal expenses if a lawsuit follows. Additionally, additional living expenses coverage assists families by paying for temporary housing, meals, and related costs if severe storm damage or fire makes a home temporarily uninhabitable.

Key Coverage Gaps and Deductible Responsibilities
Despite broad protections, standard home policies exclude specific types of damage. Flood damage is almost universally excluded from standard homeowners’ insurance and requires a separate flood insurance policy, according to reported details. Earthquake damage represents another common exclusion, despite occasional seismic activity occurring across parts of the Southeast. Homeowners must also evaluate their deductibles carefully before filing claims. A deductible dictates the exact amount an owner must pay out of pocket before the insurance provider begins covering damages. While selecting higher deductibles can lower monthly insurance premiums, it simultaneously increases the homeowner’s immediate financial responsibility when a loss occurs.