
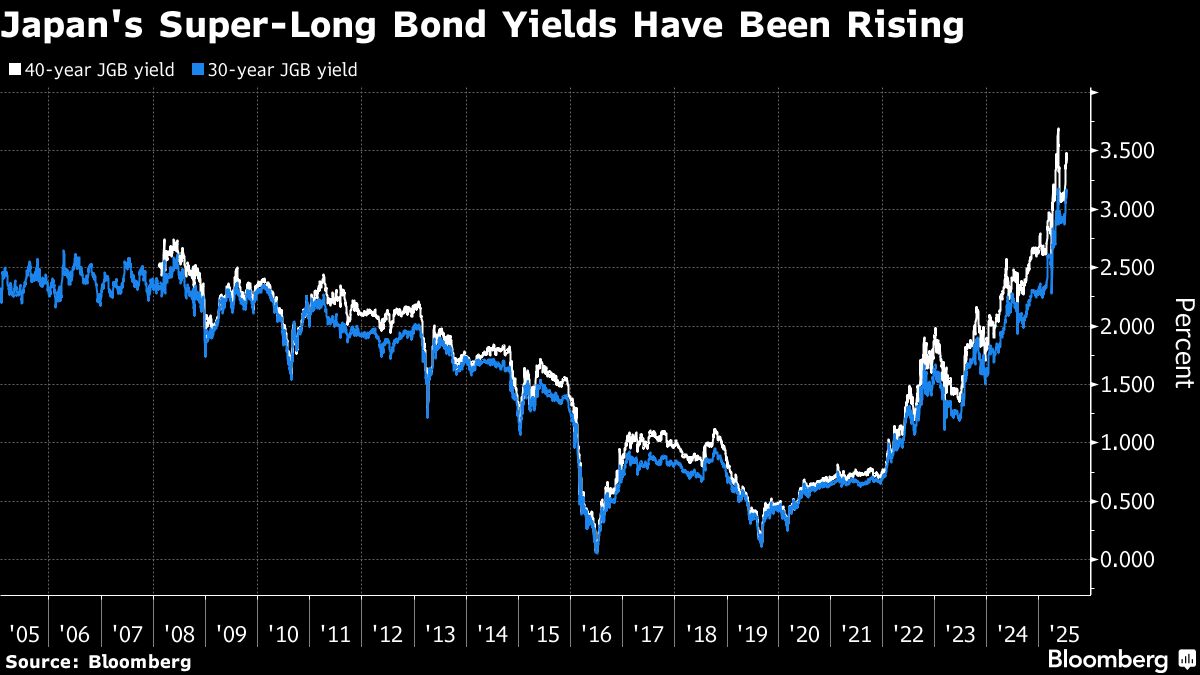
Japan Super-Long Bonds Rebound: Pre-Election Volatility
As of July 16, 2025, the landscape of Japanese government debt is experiencing notable volatility, notably within the super-long bond segment. Wednesday saw a reversal in fortunes for these instruments, which had previously endured a significant rout earlier in the week. This fluctuation is largely attributed to concerns surrounding the upcoming upper house election and its potential implications for increased government spending. Investors are closely monitoring the political climate, as election outcomes can directly influence fiscal policy and, consequently, bond yields.
Understanding the Dynamics of Super-Long Bonds
Super-long bonds, typically defined as those with maturities exceeding 10 years, are particularly sensitive to shifts in interest rate expectations and government fiscal policy.In Japan, where the Bank of Japan has maintained an accommodative monetary policy for an extended period, the yield on these longer-dated bonds plays a crucial role in the broader financial market. When investors anticipate higher government spending, frequently enough a outcome of election promises or new policy initiatives, it can lead to an increased supply of government debt. This increased supply, without a corresponding rise in demand, tends to push bond prices down and yields up.
The Impact of Election Cycles on Bond Markets
Election cycles are inherently periods of heightened uncertainty for financial markets. In Japan, the approaching upper house election has amplified these concerns. The prospect of higher government spending, a common theme in political campaigns aimed at stimulating the economy or addressing public demands, directly impacts the fiscal outlook.
Increased Debt Issuance: To fund higher spending, the government may need to issue more bonds, increasing the overall supply in the market.
Inflationary Expectations: Increased government spending can also fuel inflationary expectations, prompting investors to demand higher yields to compensate for the erosion of purchasing power over the long term.
Monetary Policy Response: Central banks may react to rising inflation or increased government borrowing by adjusting monetary policy, which can further influence bond yields.
The recent reversal in super-long bond prices suggests a complex interplay of these factors, with initial fears of increased spending giving way to a more nuanced assessment of the election’s potential economic impact.
Investor Sentiment and Market Reactions
The initial rout in super-long bonds reflected a clear investor apprehension about the fiscal implications of the election. As the election date draws nearer, market participants are attempting to price in various potential outcomes and their subsequent effects on government debt.
Analyzing the “Rout” and Subsequent Reversal
The term “rout” signifies a sharp and rapid decline in bond prices. This occurred as investors, anticipating higher government spending and potentially higher inflation, began to sell off their holdings of longer-dated bonds. Selling pressure naturally drives prices down.Though, the subsequent reversal indicates that either the initial fears were overblown, or other market forces came into play.
Re-evaluation of Spending Plans: Investors may have begun to re-evaluate the actual scale and impact of potential spending increases, finding them less detrimental than initially feared.
Safe-Haven Demand: Despite domestic political concerns, Japanese government bonds (JGBs) are often considered a safe-haven asset. In times of global economic uncertainty, demand for JGBs can increase, providing a floor for prices.
Technical Trading: Market movements are also influenced by technical factors, such as trading algorithms and the unwinding of short positions, which can contribute to price reversals.
The current market environment, characterized by a delicate balance between fiscal concerns and the inherent stability of JGBs, underscores the need for continuous monitoring of economic indicators and political developments.
The Role of the Bank of Japan
The Bank of Japan (BOJ) continues to play a pivotal role in shaping the yield curve, including that of super-long bonds. While the BOJ has maintained its ultra-loose monetary policy, including yield curve control (YCC), any significant shifts in government fiscal policy could eventually necessitate a re-evaluation of its stance.
Yield Curve Control and its Limitations
Yield curve control, a policy where the central bank targets specific yields for government bonds of different maturities, aims to keep borrowing costs low and stable. However, persistent fiscal expansion can put upward pressure on yields, potentially challenging the BOJ’s ability to maintain its YCC targets without significant intervention.
Intervention Strategies: If yields rise to rapidly, the BOJ might increase its purchases of JGBs to push prices back up and yields down. This can lead to an expansion of the central bank’s balance sheet.
Market Expectations: The effectiveness of YCC also relies heavily on market expectations.If investors believe the BOJ will defend its targets, they are less likely to push yields significantly higher.
The current situation presents a test for the BOJ’s framework, as it navigates the