
Rising Deposit Rates as a Competition Strategy May Turn into a Cost Burden-But Savings Banks Face a Tougher Challenge
- Toss (Viva Republica) has entered a partnership with South Korean savings banks to reduce their advertising expenditures and stabilize deposit acquisition, according to a June 28, 2026, report...
- The move comes as savings banks struggle with a cyclical financial burden where raising deposit rates to attract customers directly increases interest expenses.
- Savings banks face a structural dilemma between liquidity and profitability.
Toss (Viva Republica) has entered a partnership with South Korean savings banks to reduce their advertising expenditures and stabilize deposit acquisition, according to a June 28, 2026, report by Money Today. The collaboration aims to help smaller financial institutions lower marketing overhead while maintaining the liquidity necessary to fund loan operations.
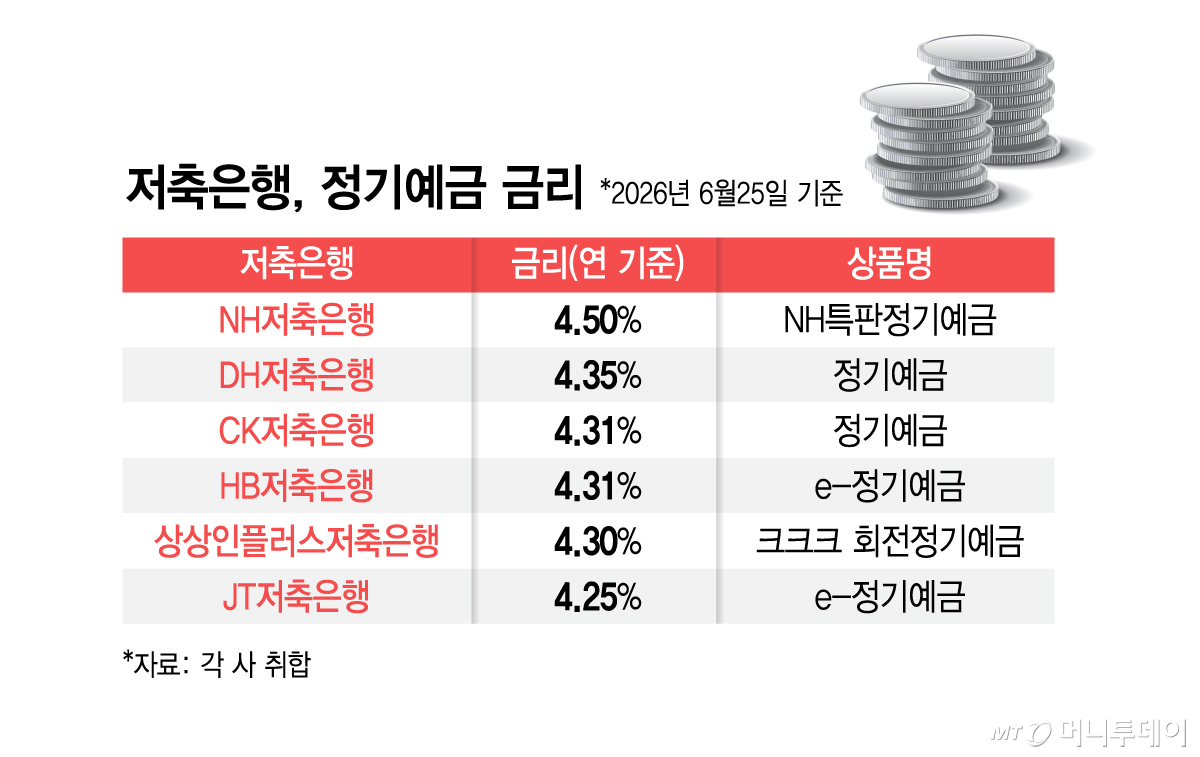
The move comes as savings banks struggle with a cyclical financial burden where raising deposit rates to attract customers directly increases interest expenses. While higher rates successfully bring in deposits, they simultaneously erode the net interest margin of the banks, according to the report.
Why are savings banks struggling with deposit rates?
Savings banks face a structural dilemma between liquidity and profitability. To secure the funds needed for lending, these institutions often engage in aggressive rate competition. When a bank raises its deposit rates above the market average, it attracts a larger volume of deposits from consumers seeking higher returns.
However, these increased rates return to the bank as a higher cost of funds. According to the source material, the interest expense incurred from these high-rate deposits puts significant pressure on the bank’s bottom line. This creates a scenario where the cost of acquiring the capital can offset the profit generated from the loans those deposits fund.
Despite these costs, savings banks cannot simply lower rates to save on expenses. A reduction in deposits leads to a contraction in loan resources, which limits the bank’s ability to grow its primary revenue stream through lending.
How does the Toss partnership reduce marketing overhead?
The partnership with Toss focuses on shifting the method of customer acquisition from broad, expensive advertising to platform-based targeting. Money Today reports that the initiative encourages banks to “Toss” their advertising costs toward the platform’s ecosystem, allowing them to reach a concentrated pool of users actively seeking financial products.
By utilizing the Toss app’s interface, savings banks can list their deposit products where users are already comparing rates and terms. This reduces the need for traditional, high-cost marketing campaigns that often yield lower conversion rates. The efficiency of the platform allows banks to attract deposits without relying solely on the most aggressive interest rate hikes, potentially easing the burden of interest expenses.
This shift represents a transition from “rate-based competition” to “access-based competition.” Instead of competing only on who can pay the highest interest, banks can compete on visibility and user experience within the Toss ecosystem.
What is the impact on the loan-to-deposit ratio?
Maintaining a stable loan-to-deposit ratio is a critical regulatory and operational requirement for savings banks. This ratio measures the amount of loans a bank has extended relative to the deposits it has taken in. If the ratio becomes too high, it indicates that the bank is over-leveraged and may lack sufficient liquidity to cover unexpected withdrawals.
The source material notes that when deposits decrease, the loan-to-deposit ratio becomes harder to manage. A shrinking deposit base forces banks to either limit new lending or find alternative, often more expensive, sources of funding.
By stabilizing deposit inflows through the Toss platform, savings banks can keep their loan-to-deposit ratios within safe regulatory limits. This stability ensures they have the necessary “ammunition” to continue issuing loans to their target customer base without triggering liquidity warnings from regulators.
How does this contrast with previous acquisition strategies?
Previously, savings banks relied heavily on a “rate war” strategy. In this model, banks would incrementally raise rates to undercut competitors, leading to a race to the top that benefited depositors but harmed bank profitability. This approach often resulted in “hot money” — deposits that would leave the bank as soon as another institution offered a slightly higher rate.
The current approach with Toss emphasizes “coexistence” and operational efficiency. By reducing the reliance on sheer rate hikes and cutting traditional advertising spend, banks aim to acquire a more stable deposit base. The focus moves from the cost of the money (the interest rate) to the cost of the acquisition (the marketing spend).
This strategy allows savings banks to manage their balance sheets more predictably. Rather than reacting to every competitor’s rate move, they can leverage the platform’s data and user flow to maintain steady deposit levels.