
30-Day Insurance Sales Fee Briefing
- Financial authorities, the insurance industry, and insurance agencies are at odds over proposed changes to insurance sales fees, delaying the finalization of a reorganization plan.
- According to sources within the insurance sector,financial regulators will conduct a briefing session April 30 to discuss the planned overhaul of insurance sales fees.
- Authorities contend that excessive sales fees, exacerbated by the introduction of the new industry accounting standard IFRS17, have fueled unhealthy business practices.
Insurance Fee Reorganization Sparks Debate Between Regulators and Agencies
Table of Contents
- Insurance Fee Reorganization Sparks Debate Between Regulators and Agencies
- Insurance Fee Reorganization: Your Questions Answered
- What’s the Core Issue at the Heart of the Debate?
- What Specific changes Are Being Proposed?
- Why Are Regulators Pushing for These Changes?
- What is IFRS17 and how does it relate to this issue?
- What is the “1200% rule” and how will it work for General Agency (GA) agents?
- What Role Does Commission Disclosure Play in This?
- Are there any international standards that support fee disclosure?
- How Does Commission Disclosure Work in Other Financial Sectors?
- Why is the GA Industry Opposing Commission Disclosure?
- What Alternatives Is the GA Industry Proposing?
- What is the GA industries argument against commission disclosure?
- Are Authorities Re-evaluating Their Position?
- What Is the Current Status of Discussions?
- What Impact Could These Changes Have on the GA Sector?
- What’s Next?
Financial authorities, the insurance industry, and insurance agencies are at odds over proposed changes to insurance sales fees, delaying the finalization of a reorganization plan.
Briefing Session Scheduled
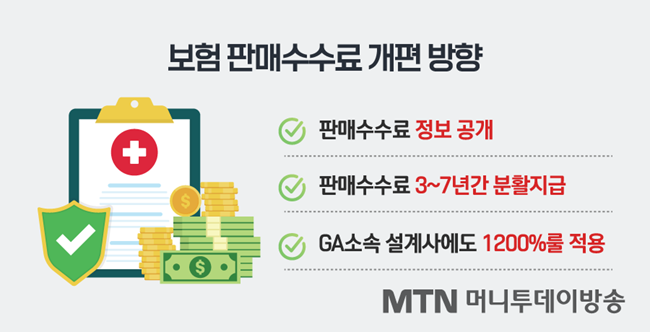
According to sources within the insurance sector,financial regulators will conduct a briefing session April 30 to discuss the planned overhaul of insurance sales fees. The session aims to gather industry feedback before a final draft is approved. The proposed changes include spreading fee payments over three to seven years,applying a “1200% rule” for General Agency (GA) agents,and mandating the disclosure of sales fee data.
regulatory Rationale
Authorities contend that excessive sales fees, exacerbated by the introduction of the new industry accounting standard IFRS17, have fueled unhealthy business practices. These include unfair agent poaching and high agent turnover. Regulators also believe that intense commission competition drives up insurance premiums and threatens the financial stability of insurers, necessitating a revised sales fee structure.
Commission Disclosure: A Point of Contention
The most contentious aspect of the proposed reorganization is the disclosure of sales fee information. Currently, insurance sales commissions, which compensate agents for selling policies, are not disclosed to policyholders. Regulators argue that transparent fee information is crucial for consumer protection.
Regulators cite international standards set by the International Association of Insurance Supervisors (IAIS), which emphasize the need to disclose cost structures to mitigate potential conflicts of interest. Thay also point to practices in major countries with supervisory systems aligned with these principles.
For example,in New York,regulations limit new payment fees (years one through four) and require that policyholders be informed of the sales allowance received by the agent from the insurance company.
Authorities also highlight that other financial sectors already mandate fee disclosure, such as brokerage fees (banks), loan platform brokerage fees (comparison platforms), and fund sales fees (Financial Investment Association).
GA Industry Resistance
The GA industry is pushing for the withdrawal of the information disclosure policy. They argue that disclosing costs not only contradicts market economy principles but also transforms the “trust relationship” with customers into one of “suspicion,” perhaps hindering insurance sales.
The GA industry also notes that other financial sectors, such as banks and securities firms, do not disclose direct fees for cost items but rather provide index forms and average figures on their websites.
As an alternative, the GA industry suggests expanding the disclosure of indirect indicators, such as the existing contract conclusion expenses index and additional insurance premium index, in a phased approach.As an example,the sales commission rate by product could be displayed in five stages: “very low,” “low,” “normal,” “high,” and “very high.”
According to a GA industry official, the fundamental question is whether disclosing agent commissions truly benefits consumers, or whether it distracts from issues such as project costs and the reasonable setting of net premium rates. The official stated that the industry is suggesting a divided alternative.
Faced with strong opposition from the GA industry, financial authorities are reportedly re-evaluating their position.
Earlier this month, Lee Se-hoon, a senior vice president at the Financial Supervisory Service, met with representatives from major GAs to discuss their concerns regarding the proposed fee reorganization.GA representatives voiced strong objections to the commission disclosure requirement.
While authorities are considering indirect disclosure methods, they remain committed to achieving the original goals of the system. Financial authorities and the GA Association are engaged in ongoing discussions through a working group, with further talks planned ahead of the briefing session.
The GA Association reports that more than 130,000 agents have signed a petition opposing the sales fee reorganization. The industry plans to initiate national petitions and group actions in the coming weeks.
A GA Association official warned that the proposed fee reorganization system could severely impact the survival of the GA sector.
Insurance Fee Reorganization: Your Questions Answered
The insurance world is currently in a state of flux.Proposed changes to insurance sales fees are sparking a major debate between regulators and the General Agency (GA) industry. This article provides a comprehensive Q&A to help you understand the key issues and the implications of these changes.
What’s the Core Issue at the Heart of the Debate?
The central disagreement revolves around proposed changes to how insurance sales fees are structured and, most substantially, whether or not these fees should be disclosed to policyholders. Financial authorities are pushing for reforms, while the GA industry is strongly resisting these adjustments.
What Specific changes Are Being Proposed?
Financial regulators are looking at a multi-pronged approach to reform. These include:
- Spreading fee payments over a longer period (3-7 years).
- Applying a “1200% rule” to general Agency (GA) agent commissions.
- Mandating the disclosure of sales fee data to policyholders. This is the most contentious point.
Why Are Regulators Pushing for These Changes?
Regulators have several key concerns that are driving this push for change. They beleive:
- Excessive Sales Fees: They contend that high sales fees, exacerbated by the new accounting standard IFRS17, are fueling unhealthy business practices.
- unfair Practices: Excessive fees contribute to unfair agent poaching and high agent turnover.
- Impact on Premiums and stability: Intense commission competition drives up insurance premiums and threatens the financial stability of insurers. Therefore, a revised sales fee structure is needed.
- Consumer Protection: Transparent fee information is crucial for consumer protection and to mitigate potential conflicts of interest.
What is IFRS17 and how does it relate to this issue?
IFRS17, a new industry accounting standard, has heightened the focus on sales fees. Regulators fear that its implementation has exacerbated existing issues with excessive fees, thereby further incentivizing the reorganization.
What is the “1200% rule” and how will it work for General Agency (GA) agents?
The “1200% rule” details were not provided in the original text. It is speculated that the “1200% rule” is a cap on first-year commissions. The specifics remain unknown to the general public.
What Role Does Commission Disclosure Play in This?
The crux of the debate lies in the proposed mandatory disclosure of sales fee information, something not currently done.Regulators believe that it is crucial for consumer protection and to address conflicts of interest. They are also following suggestions made by the International Association of Insurance supervisors(IAIS).
Are there any international standards that support fee disclosure?
Yes, regulators are citing international standards set by the International Association of Insurance Supervisors (IAIS), which emphasize the need to disclose cost structures to mitigate potential conflicts of interest. They also point to practices in major countries with supervisory systems aligned with these principles, like New York which is demanding disclosure.
How Does Commission Disclosure Work in Other Financial Sectors?
Authorities point out that other financial sectors already mandate fee disclosure. This includes:
- Brokerage Fees: Banks are required to disclose brokerage fees.
- Loan Platform Brokerage Fees: Comparison platforms are required to disclose these fees.
- Fund Sales Fees: The Financial Investment Association enforces fee disclosure.
Why is the GA Industry Opposing Commission Disclosure?
The GA industry strongly opposes the information disclosure policy, citing a number of reasons:
- Market Economy Principles: Disclosing costs is seen as contradicting market economy principles.
- Trust vs. Suspicion: Disclosing commissions,they argue,transforms the “trust relationship” with customers into one of “suspicion,” potentially harming sales.
- Other Financial Sector Practices: The GA industry notes that direct fees are not disclosed in other sectors like banks and securities firms and rather provide index forms and average figures on their websites.
What Alternatives Is the GA Industry Proposing?
As an alternative to full commission disclosure,the GA industry suggests a phased approach focusing on expanding the disclosure of indirect indicators like:
- Existing contract conclusion expenses index
- Additional insurance premium index.
- Sales commission rate by product could be displayed in five stages: “very low,” “low,” “normal,” “high,” and “very high.”
What is the GA industries argument against commission disclosure?
The GA industry official argues that the fundamental question is, whether disclosing agent commissions truly aids consumers or instead distracts from project costs and the reasonable setting of net premium rates. The industry is suggesting the alternative outlined previously.
Yes,faced with strong opposition from the GA industry,financial authorities are reportedly re-evaluating their position on these reforms. This is backed by financial authorities and the GA association engaging in discussions via a working group.
What Is the Current Status of Discussions?
The Financial Supervisory Service (FSS) is currently listening to industry feedback for the proposed fee reorganization. The major GA representatives voiced strong objections to any commission disclosure. With the GA and authorities engaged in ongoing discussions, it’s likely that the current stance is still in flux.
What Impact Could These Changes Have on the GA Sector?
The GA Association is warning that the proposed fee reorganization system could severely impact the survival of the GA sector. Over 130,000 agents signed a petition opposing the changes, and the industry plans to initiate national petitions and group actions.
What’s Next?
A briefing session is scheduled for April 30th where regulators will discuss the planned changes with industry participants. Further talks are planned between financial authorities and the GA Association through a working group to find common ground. The outcome will ultimately shape the future of insurance sales practices. Further developments will happen as the discussion continues.