
Hanwha Solutions’ IFRS18 Impact on KOSDAQ Interlock
- SEOUL — Proposed changes to international accounting standards are raising concerns about potential manipulation of corporate earnings, particularly among smaller companies, according to a recent analysis.
- The discussion was fueled, in part, by a controversy surrounding Hanwha Solution's fourth-quarter earnings.
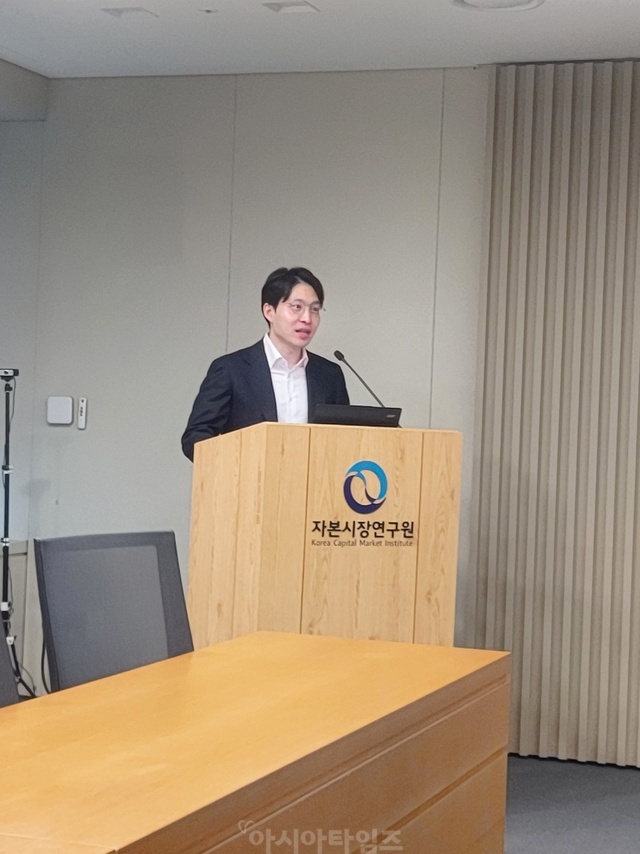
- Lee sang-ho, a researcher at the Korea Institute of Capital Markets, addressed the issue during a briefing in Seoul.
IFRS 18 Accounting Changes Spark Debate Over Earnings Transparency
Table of Contents
- IFRS 18 Accounting Changes Spark Debate Over Earnings Transparency
- IFRS 18 Accounting Changes: Your Questions Answered
- What are IFRS 18 Accounting Changes?
- What’s the Main Issue with IFRS 18?
- How Will IFRS 18 Change How Operating Profit is Calculated?
- Can you provide an example of how IFRS 18 might impact reported earnings?
- How does IFRS 18 differ from current Korean Accounting Standards (K-IFRS)?
- What are the Potential Concerns with IFRS 18 in the Korean Market?
- How could IFRS 18 affect investors?
- What was Hanwha Solution’s response to the concerns regarding their reported earnings?
SEOUL — Proposed changes to international accounting standards are raising concerns about potential manipulation of corporate earnings, particularly among smaller companies, according to a recent analysis. The debate centers on the upcoming implementation of International Financial Reporting Standards (IFRS) 18, slated for 2027, which redefines how operating profit is calculated.
Concerns Raised Over “Fake Earning Surprise”
The discussion was fueled, in part, by a controversy surrounding Hanwha Solution‘s fourth-quarter earnings. While the company reported an operating profit of ₩100 billion, questions arose regarding a ₩96.7 billion figure that was not readily traceable. While the company defended its accounting practices as legitimate, the incident highlighted potential vulnerabilities in current reporting methods.
Lee sang-ho, a researcher at the Korea Institute of Capital Markets, addressed the issue during a briefing in Seoul. He cautioned that the introduction of IFRS 18, as currently planned, could exacerbate these concerns, especially for companies listed on the KOSDAQ market.

IFRS 18: Redefining Operating Profit
Under IFRS 18, the criteria for determining operating profit will shift. The International Accounting Standards Board (IASB) will categorize business activities into sales, investment, and finance. IFRS 18 will then define operating profit as encompassing items that do not fall into the investment or finance categories. This means that one-time gains and losses, such as damages, foreign exchange fluctuations, and donations, could be included in operating profit calculations.
In the case of Hanwha solution, the company attributed ₩102.8 billion of its operating profit to the “Other” category in its fourth-quarter report.
The announcement of a ₩107 billion operating profit led to a 6.45% increase in Hanwha Solution’s stock price. However, the inclusion of a ₩96.7 billion sale amount within the “Other” category raised eyebrows.
Hanwha Solution engages in urban development projects, and its legal accounting allows for the inclusion of sale profits as operating profit.
Divergence from Korean Accounting Standards
Lee emphasized that IFRS 18’s definition of operating profit differs considerably from the existing Korean International Financial Reporting Standards (K-IFRS). The key difference lies in the judgment of what constitutes “main operating activities.”
Currently, K-IFRS calculates operating profit by subtracting sales costs and administrative expenses from sales revenue.
Lee argued that the current K-IFRS operating profit serves as a crucial indicator of current profitability and has been effectively utilized in the korean capital market for the past two decades. He suggested that IFRS 18 might be more challenging to interpret and utilize effectively, implying that K-IFRS offers superior characteristics.
Limited Disclosure and Monitoring
Lee pointed to limitations in corporate disclosure practices, noting that onyl a small percentage of KOSPI 200 companies (4%) define their actual performance measurements through self-disclosure, and only 13% provide operating profit forecasts. He also highlighted the limited analyst coverage of KOSDAQ companies and their vulnerability due to a recent focus on the U.S. market.
“It is indeed clear that the possibility of very aggressive financial reporting practices will be made in mind,especially in small and medium-sized stocks with limited monitoring of the market and the media,” Lee said.
He also expressed concern that a conservative corporate investor relations (IR) culture and a weak information brokerage base in the Korean capital market could hinder the effective functioning of business and information based on management autonomy under IFRS 18.
Company Response
During an earnings call,Hanwha Solution CFO Yoon An-sik stated that the company’s turnaround to profitability reflected the sale of the Ulsan housing site and that real estate development falls within the scope of the company’s articles of incorporation,justifying its inclusion in operating profit.
Debate Over the Best Approach
Lee acknowledged that IFRS 18 aligns the definition of operating profit with many European countries and simplifies the process of judging main business activities. however,he questioned whether adopting the standard is the right choice for Korea,given its specific market conditions.
He stressed that investors value profit and cost information generated from a company’s core business activities because the value of the company is derived from future cash flow.
Lee concluded by suggesting that rather of simply adopting IFRS 18, it might be more reasonable to adapt and improve the existing K-IFRS framework to better suit the Korean capital market.
He recommended developing clear standards and methods for understanding a company’s continuous performance after the implementation of IFRS 18 and improving the structure and subdivision of performance disclosure forms.
IFRS 18 Accounting Changes: Your Questions Answered
What are IFRS 18 Accounting Changes?
IFRS 18 represents upcoming changes to International Financial Reporting Standards. These changes, set to be implemented in 2027, will redefine how companies calculate and report their operating profit. These changes are raising a significant amount of debate and concern among financial experts regarding the potential impact on earnings openness,especially for smaller companies.
What’s the Main Issue with IFRS 18?
The primary concern revolves around the potential for manipulation of corporate earnings. Under IFRS 18,the criteria for determining operating profit will shift,wich may make it easier for companies to include one-time gains and losses in their operating profit calculations,potentially creating a misleading picture of a company’s financial performance.This could lead to what some call a “fake earnings surprise”.
How Will IFRS 18 Change How Operating Profit is Calculated?
IFRS 18 will categorize business activities into three main areas: sales, investment, and finance. Operating profit will then be defined by excluding items that fall within the investment or finance categories. This could mean that one-time gains and losses, such as damages, foreign exchange fluctuations, and donations, can be included in operating profit, which is a major shift from how operating profit is currently calculated under legacy standards such as K-IFRS.
Can you provide an example of how IFRS 18 might impact reported earnings?
Certainly. The article highlights the example of Hanwha Solution. The company reported a core operating profit of ₩100 billion, with ₩96.7 billion being questioned. Specifically, the company attributed ₩102.8 billion of its operating profit to the “Other” category. This ultimately led to a stock price increase of 6.45%, sparking concerns about the transparency and the true nature of their profit.
How does IFRS 18 differ from current Korean Accounting Standards (K-IFRS)?
The key difference lies in how “main operating activities” are judged. K-IFRS currently calculates operating profit by subtracting sales costs and administrative expenses from sales revenue. Under IFRS 18, the definition of operating profit is broader, potentially including items that K-IFRS would exclude.
What are the Potential Concerns with IFRS 18 in the Korean Market?
One of the most significant concerns is the potential for reduced transparency and increased opportunities for manipulation. Several factors contribute to this:
- Limited Disclosure: Only a small number of KOSPI 200 companies define performance measurements through self-disclosure, and an even smaller percentage provide operating profit forecasts.
- Limited Analyst Coverage: KOSDAQ companies have limited analyst coverage, making it harder for investors to scrutinize financial reports.
- Conservative IR Culture: A conservative investor relations culture may hinder effective interaction and understanding of financial performance
How could IFRS 18 affect investors?
The adoption of IFRS 18 could make it more challenging for investors to assess a company’s true profitability. The inclusion of one-time gains and losses, or profits derived from non-core business activities, in operating profit calculations could potentially obscure a company’s underlying financial health. Investors may find it harder to compare financial performance across different companies if reporting standards become less uniform.
What was Hanwha Solution’s response to the concerns regarding their reported earnings?
During an earnings call, Hanwha Solution’