
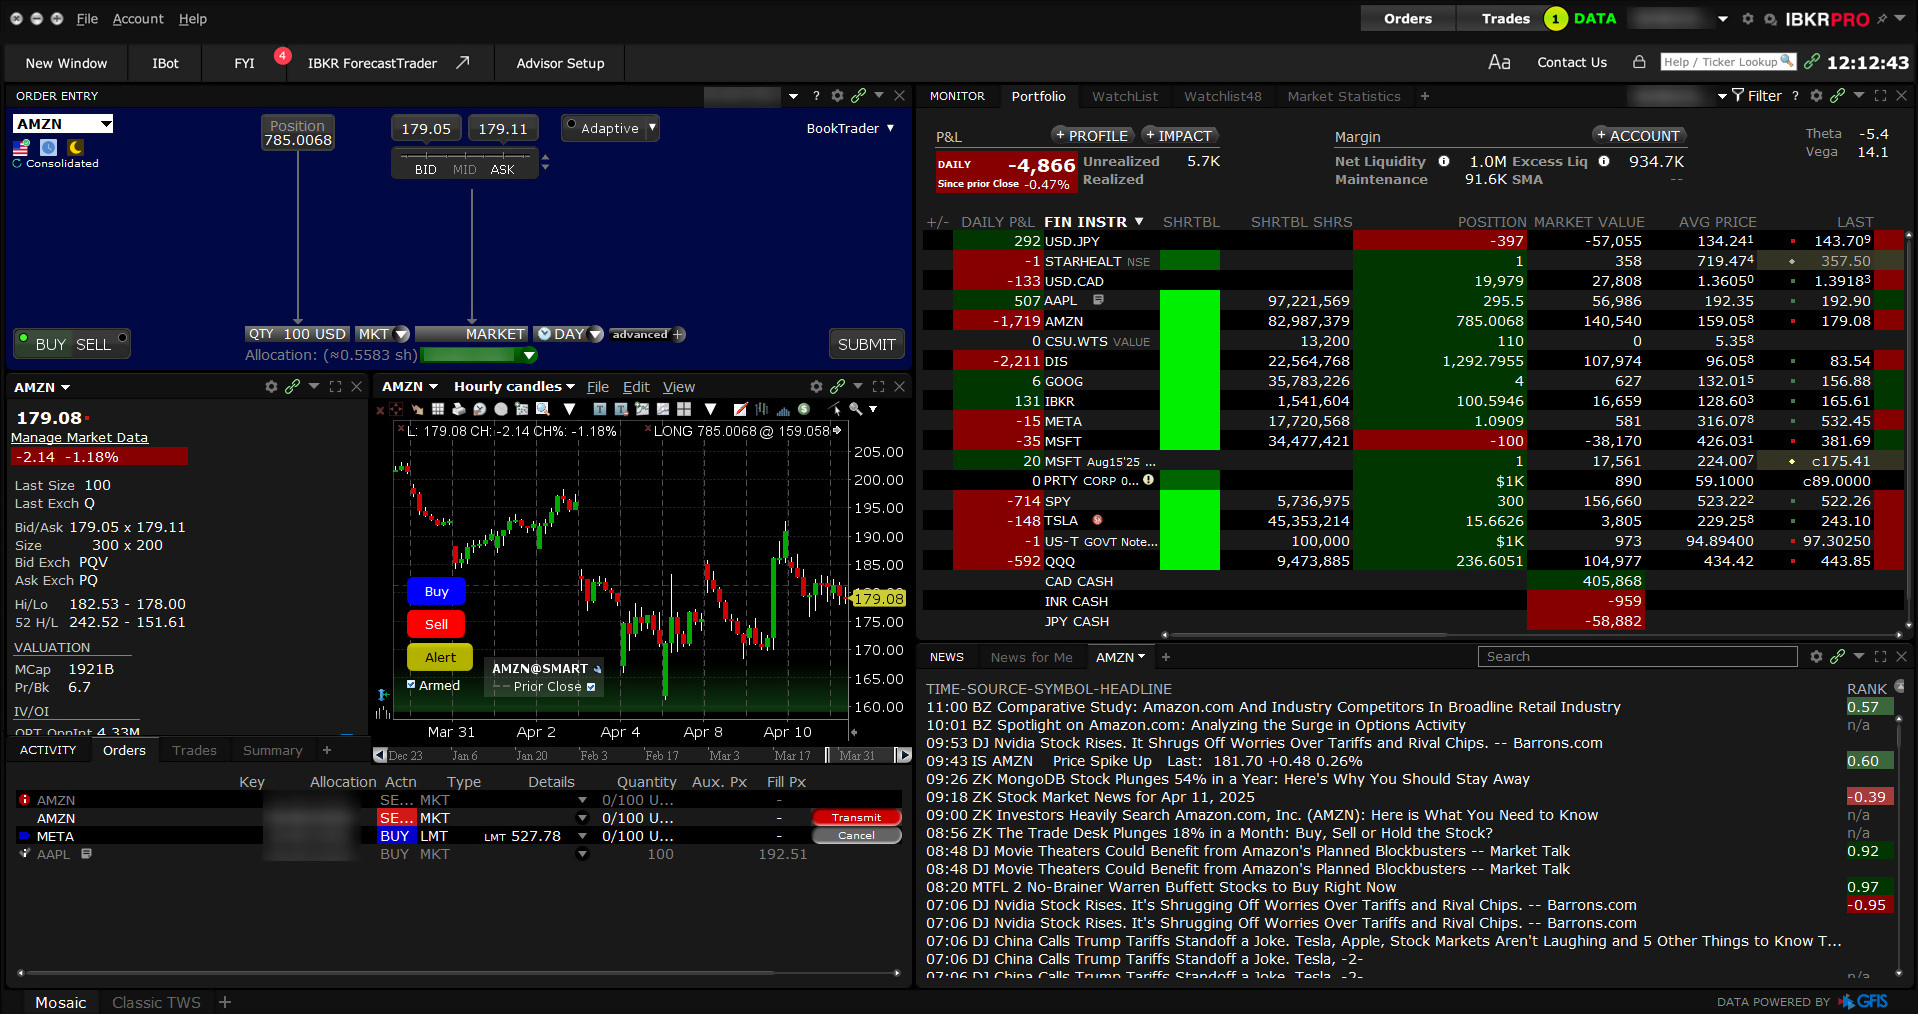
Interactive Brokers Trading Platform Overview and Quant Guild Community
Market neutral trading strategies have drawn renewed attention across quantitative finance communities as algorithmic platforms scale execution speeds. Quantitative finance networks report that systematic traders are increasingly deploying these hedging techniques to isolate alpha while neutralizing broad market direction exposure.
According to educational releases and community briefings from algorithmic trading platforms such as Quant Guild, market neutral frameworks rely on balancing long and short positions to capture relative value discrepancies. Practitioners frequently utilize statistical arbitrage and pairs trading models to profit from temporary pricing inefficiencies between correlated assets.
Implementing Systematic Hedges
Execution mechanics require strict adherence to quantitative parameters and automated risk controls. Traders use historical pricing data and covariance matrices to construct portfolios with a beta close to zero, effectively insulating the strategy from systemic market downturns.
Platform resources note that backtesting infrastructure remains critical before deploying capital into live environments. Developers evaluate slippage, execution latency, and transaction costs to ensure that theoretical spreads translate into net positive returns after fees.
Risk Management and Execution Infrastructure
Execution platforms emphasize that maintaining a market neutral posture demands continuous rebalancing as asset correlations shift. Automated risk engines monitor portfolio exposure in real time, triggering adjustments whenever allocation drift exceeds predefined thresholds.
Industry discussions highlight that while these strategies mitigate directional risk, they remain vulnerable to model risk, liquidity shocks, and sudden structural breaks in asset correlation. Quantitative developers continue to refine factor models to address these execution challenges.