
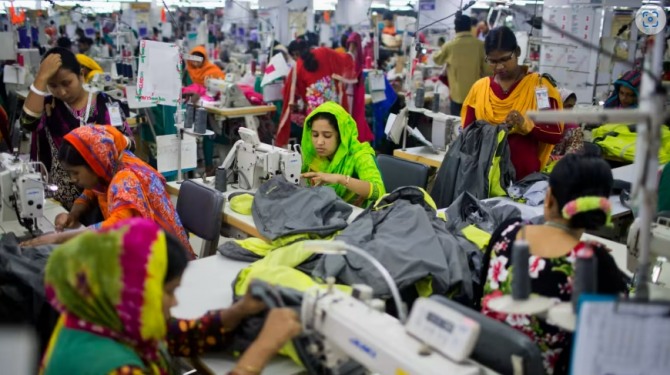
Maintaining Asian Manufacturing Amid De-Industrialization Crisis
- Developing countries in Asia are confronting a rapid de-industrialization crisis, fueled by teh influx of low-priced products from China and increasingly stringent Western trade barriers, according to a...
- The Organization for Economic Cooperation and Progress (OECD) projects a decline in global economic growth from 3.3% in 2024 to 3.1% in 2025.
- This early post-industrialization phenomenon in Asia reflects structural shifts in globalization.
Asian Economies Face De-industrialization Amidst Chinese Competition, Trade Barriers
Table of Contents
- Asian Economies Face De-industrialization Amidst Chinese Competition, Trade Barriers
- Asian Economies Face De-industrialization: A Q&A
- What is Driving De-industrialization in Asian Economies?
- How Does China’s Manufacturing Impact Asian Countries?
- What Trade Barriers Are Affecting Asian Economies?
- What Economic Slowdown is Expected, and How Does it Impact Asia?
- Which Asian Countries Are Most Affected?
- What are the Strategic Options for Asian Countries in Response to De-industrialization?
- What are the Challenges of Transitioning to a Service-Based Economy?
- What Actions should Asian Countries Take?
- What are the Potential Risks of De-industrialization?
- Are There opportunities for Export-Oriented Industrialization?
- Key Differences in Manufacturing’s Contribution to GDP
Date: March 26, 2025
Developing countries in Asia are confronting a rapid de-industrialization crisis, fueled by teh influx of low-priced products from China and increasingly stringent Western trade barriers, according to a report.
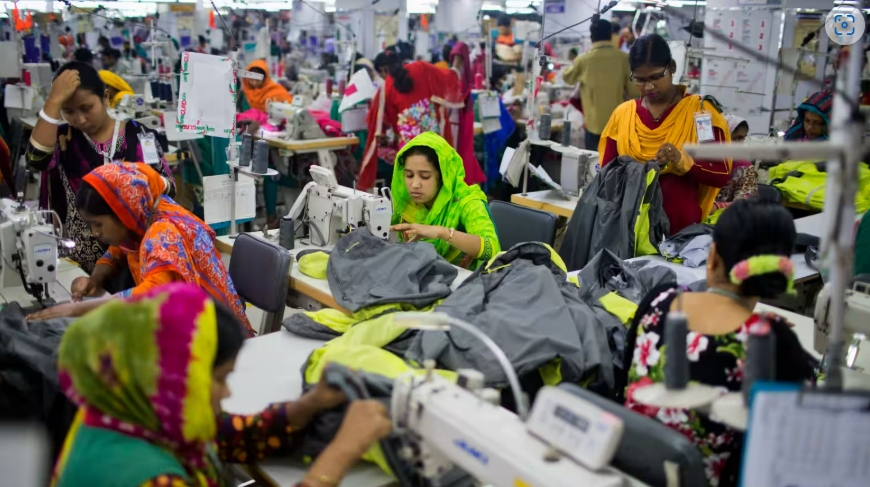
The Organization for Economic Cooperation and Progress (OECD) projects a decline in global economic growth from 3.3% in 2024 to 3.1% in 2025. This slowdown is expected to negatively impact Asian economies, which are heavily reliant on exports.
This early post-industrialization
phenomenon in Asia reflects structural shifts in globalization. The proportion of manufacturing in developing countries is decreasing at lower income levels compared to developed nations, a trend that has accelerated recently.
In Brazil, the proportion of manufacturing industries to gross domestic product (GDP) fell sharply from 30% in the 1980s to 12% in the 2000s. Malaysia, thailand, and Indonesia, early industrializers in Asia, maintained a notable manufacturing base, accounting for more than 20% of GDP over the past decade. However, this foundation is now threatened by the influx of inexpensive Chinese goods.
Thailand has seen more than 3,000 companies close since 2021, with the steel industryS utilization rate dropping to 28%. Indonesia’s textile industry and toy manufacturers in India are also experiencing factory closures and job reductions. The situation is expected to worsen as China’s low-cost exports flood neighboring Asian countries due to increased Western trade barriers and slowing consumption within China.
Asian countries face a strategic dilemma: should they embrace China’s comparative advantage in manufacturing and transition to a service-driven growth model, or should they prioritize re-industrialization? A balanced approach is highly likely the most effective solution.
Historically, the manufacturing industry has absorbed large numbers of unskilled workers from agriculture, driving productivity improvements through capital accumulation, technology development, and economies of scale. Thes gains have been arduous to replicate in the labor-intensive service sector.
However, the COVID-19 pandemic spurred significant expansion in service trade, driven by the rapid spread of details and communication technology (ICT) and digital channels. The service sector is increasingly exhibiting characteristics of the manufacturing industry, with enhanced competitiveness and greater potential for expansion and automation.
Two key considerations arise when transitioning to a service-based economy. First, low-end services that absorb unskilled and low-skilled labor tend to have low productivity. Second, high-skilled services with high productivity potential require advanced technology that most Asian developing countries do not yet possess. Even in India, only 1% of the labor force is directly employed in the productive ICT service sector.
Thus, Asian countries should prioritize investments in advanced digital infrastructure, human capital development, and strengthening their technology base. Simultaneously, policymakers should support industries in adapting to the new manufacturing habitat while preventing a rapid decline in the manufacturing sector.
Rather than implementing temporary industrial protection measures, a more effective approach involves addressing the root causes of manufacturing weakness. Manny of these solutions, such as human capital accumulation and infrastructure investment, are also essential for building a robust service sector.
Without this dual approach, there is a risk of productivity and wage stagnation as unemployed factory workers move to agriculture or low-skilled service jobs.Brazil’s experience demonstrates that excessive dependence on services without a trained labor force can delay economic convergence for developing countries.
While opportunities for export-oriented industrialization are diminishing due to increased protectionism, China’s manufacturing dominance, and capital intensity in manufacturing, these opportunities have not entirely disappeared for Asian developing countries.
The diversification of supply chains and the rise of green and technology industries present growth opportunities for Asian countries. They should capitalize on these opportunities while preparing for a transition to service-based models.
Asian Economies Face De-industrialization: A Q&A
Date: March 26, 2025
What is Driving De-industrialization in Asian Economies?
Asian economies are currently experiencing de-industrialization, a trend accelerated by several factors. These include the influx of low-priced goods from china and increasingly stringent Western trade barriers. This “early post-industrialization” is occurring at lower income levels compared to developed nations.
How Does China’s Manufacturing Impact Asian Countries?
China’s comparative advantage in manufacturing, coupled with its ability to produce inexpensive goods, considerably impacts neighboring Asian countries. This has led to factory closures and job reductions in industries like textiles and toys.
What Trade Barriers Are Affecting Asian Economies?
Increasing Western trade barriers are contributing to de-industrialization in Asia. These barriers,combined with slowing consumption within China,are making it difficult for Asian countries to compete in the global market.
What Economic Slowdown is Expected, and How Does it Impact Asia?
The Organization for Economic Cooperation and Progress (OECD) projects a decline in global economic growth from 3.3% in 2024 to 3.1% in 2025.this slowdown is expected to negatively impact Asian economies, wich are heavily reliant on exports.
Which Asian Countries Are Most Affected?
Countries like Thailand, Indonesia, Malaysia, and India are notably affected. Thailand has seen over 3,000 company closures since 2021. Indonesia’s textile and India’s toy manufacturers are experiencing factory closures and job losses.
What are the Strategic Options for Asian Countries in Response to De-industrialization?
Asian countries face a strategic choice: embrace China’s manufacturing dominance and transition to a service-driven model, or prioritize re-industrialization.A balanced approach is likely the most effective solution.
What are the Challenges of Transitioning to a Service-Based Economy?
Several challenges arise. Low-end services frequently enough have low productivity, and high-skilled services require advanced technology, which many Asian developing countries lack. For example, only 1% of India’s labor force is directly employed in the productive ICT service sector.
What Actions should Asian Countries Take?
- invest in digital infrastructure: Focus on building advanced digital infrastructure.
- Develop human capital: Prioritize human capital progress and strengthen the technology base.
- Support industries: Support industries in adapting to the new manufacturing landscape.
- Address root causes: Address the core issues of manufacturing weakness, focusing on human capital accumulation and infrastructure investment.
What are the Potential Risks of De-industrialization?
Without a dual approach of supporting both manufacturing and services, there’s a risk of productivity and wage stagnation as unemployed factory workers move to low-skilled service jobs.Excessive dependence on services without a trained labor force can delay economic convergence.
Are There opportunities for Export-Oriented Industrialization?
While opportunities for export-oriented industrialization are diminishing, they haven’t entirely disappeared. Diversification of supply chains and the rise of green and technology industries present growth opportunities for Asian countries.
Key Differences in Manufacturing’s Contribution to GDP
The following table summarizes how manufacturing has changed:
| Country | Manufacturing % of GDP (1980s) | Manufacturing % of GDP (2000s) |
|---|---|---|
| Brazil | 30% | 12% |
| Malaysia, Thailand, Indonesia | N/A | Maintained over 20% for the past decade |