
Marketplace Plans: Higher Costs & Cost-Sharing
- Consumers purchasing health insurance through the Affordable Care act (ACA) Marketplace may see changes in their plans and costs starting in 2026.
- The changes, stemming from a program Integrity Rule, involve the actuarial value (AV) of plans.
- Individual and small-group market plans, except expanded bronze, can now vary by +2/-4 percentage points.
Get ready for shifts in your ACA marketplace plan! Beginning in 2026, changes finalized by CMS could lead to higher out-of-pocket expenses or lower premiums for consumers. These updates affect how insurers set actuarial value (AV) targets, the percentage of healthcare costs a plan covers-impacting plan costs and, potentially, the health insurance landscape. The new rules allow insurers greater flexibility, which may make it challenging to compare plans and their associated costs. This directly addresses the question of higher costs and cost-sharing in current ACA plans. For those seeking the best deals, news Directory 3 shares vital insights into the implications of these marketplace adjustments, and what it means for consumers. Discover what’s next …
ACA Marketplace Plan Changes Could Impact Consumer Costs
Consumers purchasing health insurance through the Affordable Care act (ACA) Marketplace may see changes in their plans and costs starting in 2026. The Centers for Medicare and Medicaid Services (CMS) finalized revisions to marketplace plans that could incentivize insurers to offer less generous coverage.
The changes, stemming from a program Integrity Rule, involve the actuarial value (AV) of plans. AV represents the average percentage of healthcare costs a plan covers. Plans are categorized into metal tiers: bronze (60%), silver (70%), gold (80%), and platinum (90%).
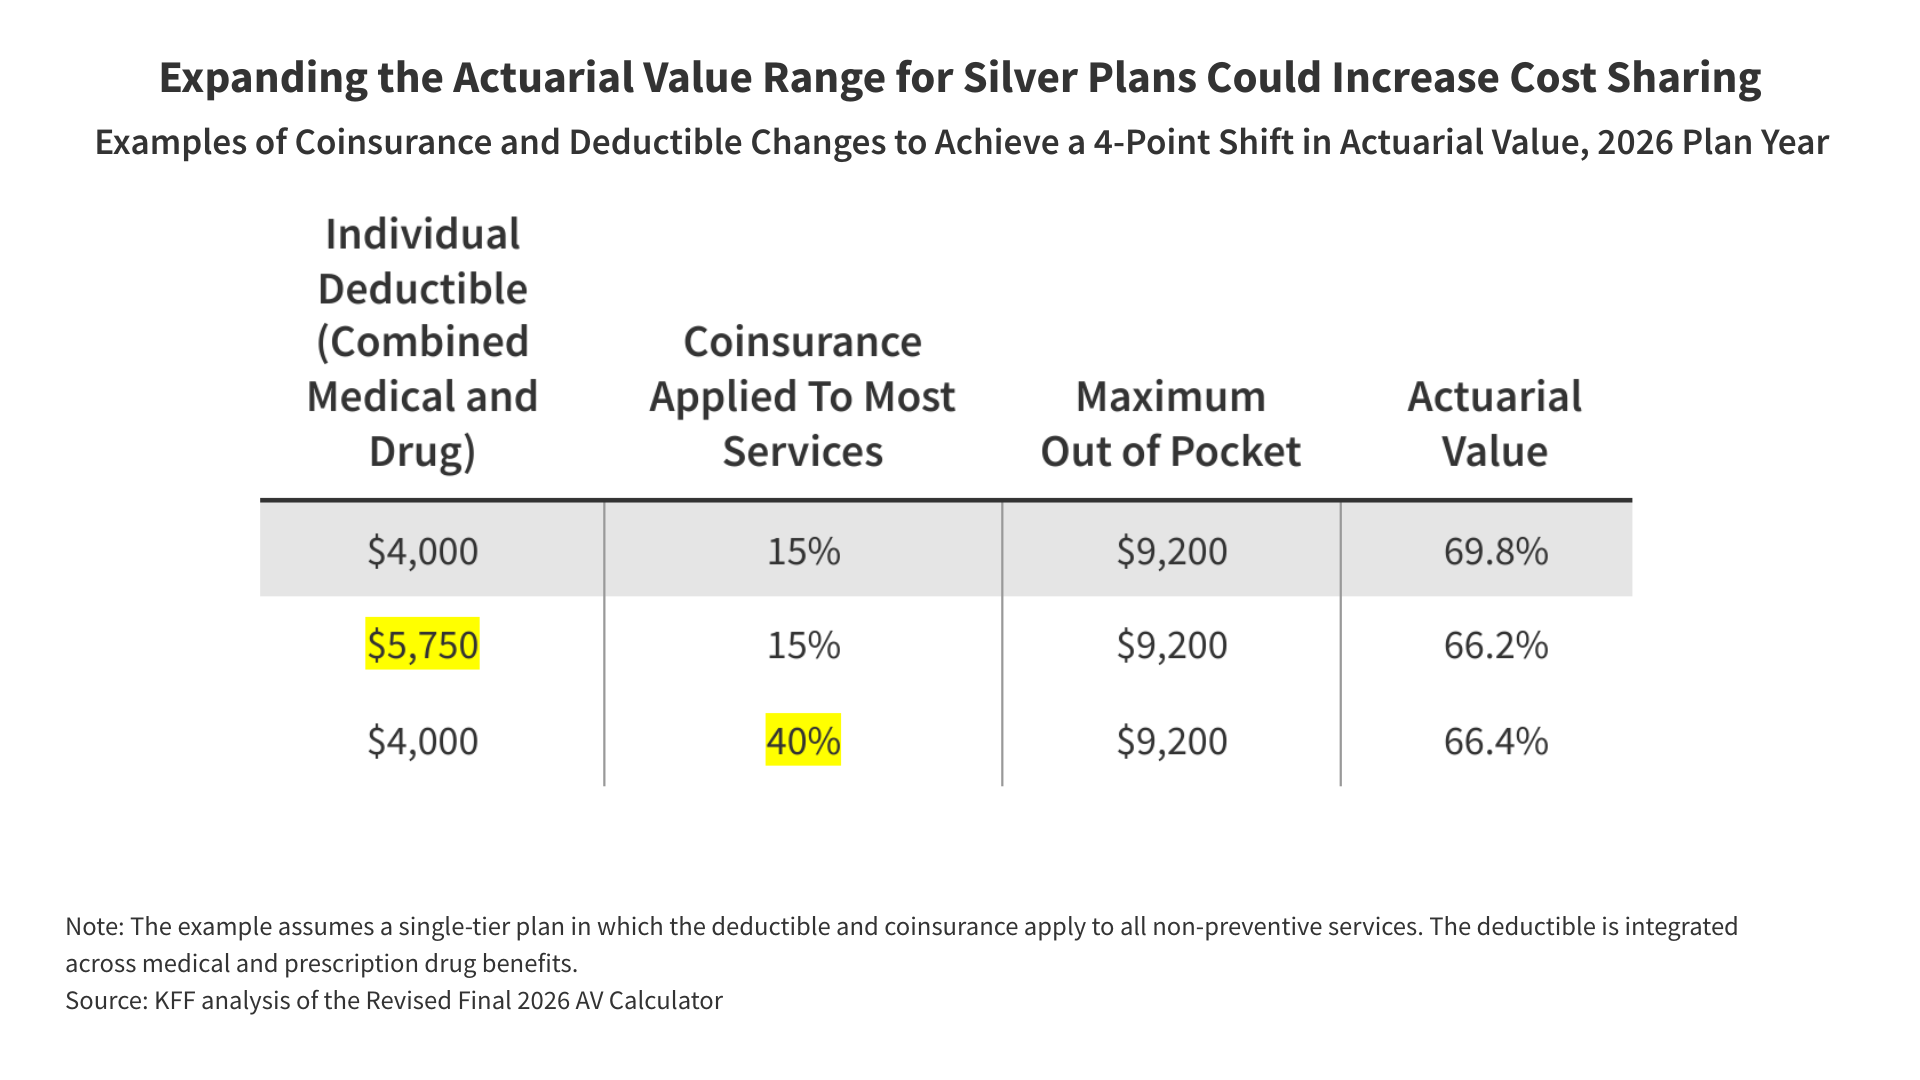
The new rule expands the allowable range for AV targets. Individual and small-group market plans, except expanded bronze, can now vary by +2/-4 percentage points. For silver plans with cost-sharing reductions, the range is +1/-1 percentage points. This flexibility allows insurers to lower the AV of their plans while maintaining the same metal level.
For example, a silver plan currently requires a 70% AV. Under the new rule, an insurer could offer a plan with a higher deductible or coinsurance that results in a lower AV, while still classifying it as silver. The One Big Beautiful Bill Act would codify these ranges into law.
While some consumers might see lower premiums, the trade-off could be higher out-of-pocket expenses. This notably affects the roughly 8% of marketplace enrollees who do not qualify for premium assistance.
Standardized plans, also known as “easy pricing” plans on HealthCare.gov, were designed to simplify cost comparisons. However, the wider AV range may make it harder for consumers to discern the true value of non-standardized plans.
What’s next
Insurers will decide how to adjust their plan designs within the new AV ranges for the 2026 plan year. Consumers should carefully compare plans, paying attention to both premiums and potential out-of-pocket costs, before making a selection during open enrollment.