
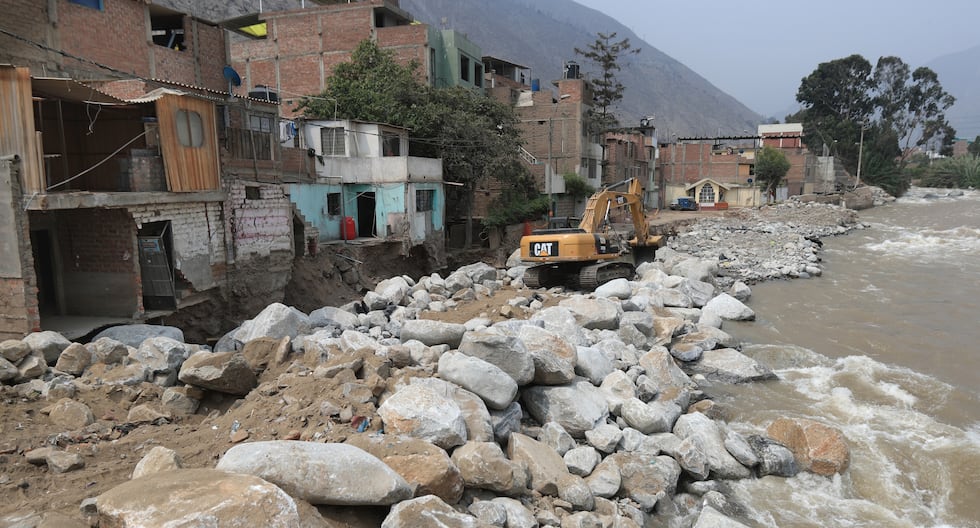
Peruvian insurers expect up to S/ 5 billion in El Niño payouts
- Peruvian insurance companies expect to pay between S/ 3,500 million and S/ 5,000 million in indemnifications for damages caused by the El Niño phenomenon between late 2026 and...
- While the insurance sector prepares for billions in claims, the total economic toll of the climate event is expected to be significantly higher.
- Furthermore, policyholders face additional costs through deductibles, meaning that insurance companies do not cover the full value of every claim.
Peruvian insurance companies expect to pay between S/ 3,500 million and S/ 5,000 million in indemnifications for damages caused by the El Niño phenomenon between late 2026 and early 2027, according to Alberto Vásquez, general manager of La Positiva Seguros. This projected payout, as reported by Gestión, covers critical infrastructure including irrigation projects, dams, hydroelectric plants, and transmission systems.
The Gap Between Insured Damages and Total Economic Impact
While the insurance sector prepares for billions in claims, the total economic toll of the climate event is expected to be significantly higher. Estimates from the BCP (Banco de Crédito del Perú) indicate that El Niño could cause total damages of approximately S/ 16,000 million. This figure represents roughly 0.5% of the national GDP in 2026 and 0.8% in 2027, a disparity explained by the fact that not all infrastructure in the country is covered by insurance policies.
Furthermore, policyholders face additional costs through deductibles, meaning that insurance companies do not cover the full value of every claim. La Positiva Seguros alone anticipates disbursing approximately S/ 250 million to address these losses.
Escalating Risks of Extraordinary Magnitude
The Multisectoral Commission for the National Study of the El Niño Phenomenon (ENFEN) has significantly increased its probability assessments regarding the intensity of the event. As of mid-October 2026, the likelihood of an extraordinary magnitude event along the Peruvian coast was placed at 88% for October, 85% for November, and 80% for December.
These projections are notably higher than those issued by the agency on September 14. Similar trends are observed for the global El Niño in the central Pacific, with probabilities of a strong-magnitude event reaching 80% for October, 85% for November, and 83% for December.
Operational Challenges for Insurance Providers
The insurance industry is bracing for a high volume of claims affecting diverse sectors. Bernardo Klinge, director of general insurance at Mapfre Perú, noted during the Apecose International Insurance Meeting in Ica that the damage will likely extend to homes, businesses, and agricultural crops. Klinge emphasized that in the southern highlands, the concern is drought, which contrasts with the flood risks often anticipated in the northern regions.
We are going to have thousands of cases of people affected, mainly due to damage to homes, businesses, in the case of agriculture as well; and for crops in the areas, typically in the southern highlands, where there is drought. All of this will generate a need for attention on what is covered by an insurance policy.
Bernardo Klinge, Mapfre Perú
Companies typically manage two types of coverage: property damage insurance, which covers the value of assets, and business interruption insurance, known as lucro cesante. The latter compensates for gross profit lost when a company is forced to stop production or sales due to a catastrophe. Francisco Rodríguez Larraín, president of Apecose, noted that while property damage coverage is standard, business interruption coverage is an additional elective layer provided by some firms.
Contingency Planning and Future Vulnerability
Industry leaders are currently reviewing their protocols to manage the expected surge in demand for services. Mapfre Perú has indicated that it is refining its contingency plans to interact more effectively with clients, particularly those managing large-scale risks. Mario Potestá, CEO of Rímac Seguros, has suggested that the country requires a protection gap management map to provide a clearer diagnostic of national vulnerability.
The capacity of the state to manage such large-scale disasters remains a point of concern for industry stakeholders. Klinge stated that the government has historically struggled to ensure that existing resources reach those in need in a timely manner. It remains unclear how the coordination between private insurance payouts and public relief efforts will function as the country approaches the peak of the forecasted weather event.