
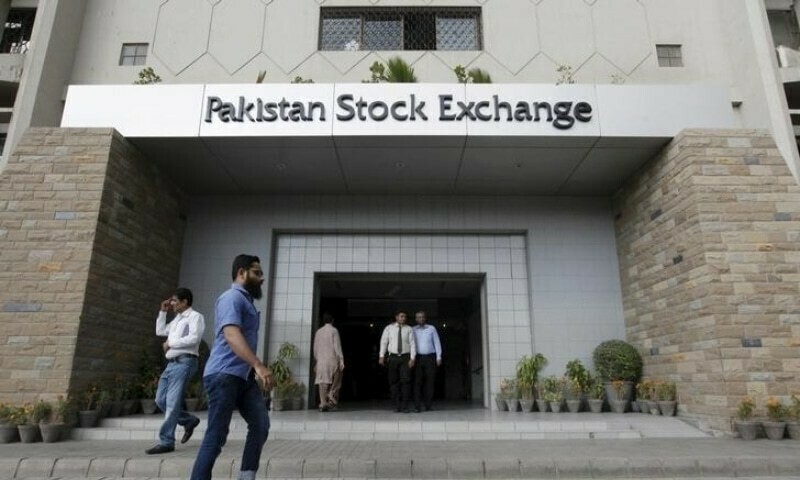
PSX May Recovery: 7.5pc Rise Amidst India Conflict
- The Pakistan Stock Exchange (PSX) saw renewed buying interest across sectors, driving the KSE 100 index upward.
- Anticipated relief for the agricultural sector, coupled with measures designed to stimulate exports and industrial growth in the upcoming budget, restored investor confidence.This led to value hunting, pushing...
- The government has confirmed that the federal budget for 2025-26 will be revealed on June 10, with no further delays expected.
The Pakistan Stock Exchange (PSX) experienced a remarkable turnaround in May, with the KSE 100 index soaring by 7.5% amidst receding geopolitical tensions and increased clarity surrounding the federal budget. Investor confidence was bolstered by anticipated relief measures for the agricultural sector and plans to stimulate exports, driving critically important value hunting and a substantial rise in average daily traded volume. The market saw its largest single-day gain ever, signaling a robust recovery following the opening at 112,820 before it rose to a high of 120,699. The State Bank of Pakistan (SBP) saw reserves rise, with banks, fertilizer, and E&P sectors contributing positively.News Directory 3 is your source for financial market updates. The upcoming federal Budget FY26 and the Monetary Policy Committee (MPC) meeting in June hold the keys to further market movement. Discover what’s next for the PSX.
KSE 100 index Climbs Amid Budget Clarity, Easing Tensions
The Pakistan Stock Exchange (PSX) saw renewed buying interest across sectors, driving the KSE 100 index upward. Easing geopolitical tensions and greater clarity surrounding the federal budget announcement helped boost market sentiment.
Anticipated relief for the agricultural sector, coupled with measures designed to stimulate exports and industrial growth in the upcoming budget, restored investor confidence.This led to value hunting, pushing the index to nearly 120,000 by the end of the month.
The government has confirmed that the federal budget for 2025-26 will be revealed on June 10, with no further delays expected.
According to AKD Securities Ltd, the market traded within a narrow range due to uncertainty about potential revenue measures in the upcoming budget. The KSE-100 index ultimately increased by 588 points, or 0.49pc, closing the week at 119,691.
Market participation increased, with average daily traded volume rising by 34.6pc to 662 million shares, compared to 492 million shares the previous week.
The International Monetary Fund (IMF) concluded its staff mission on the Federal budget FY26, describing discussions as constructive with further deliberations ongoing.
China has reportedly assured Pakistan of $3.7 billion in refinancing for June, which should enable Pakistan to meet the IMF’s foreign exchange reserves target of $14 billion by the end of FY25. The government is also nearing completion of a financing agreement aimed at addressing circular debt in the power sector.
the rupee experienced a slight depreciation of 0.02pc, closing at Rs282.02 against the U.S. dollar.
Arif Habib Ltd (AHL) noted that the PSX experienced volatility in May, largely due to geopolitical tensions.
The PSX posted a return of 7.51pc in May. After opening at 112,820, the benchmark index reached a high of 120,699 before falling to a low of 101,599, eventually closing the month at 119,691, marking an overall gain of 8,365 points.
As geopolitical concerns subsided, investor confidence returned, leading to a strong market rebound. The index surged by 10,123 points (9.45pc) in a single day, closing at 117,298, representing the largest single-day gain in the index’s history in both absolute and percentage terms.
Positive economic developments, including the International Monetary fund’s approval of $1 billion under the Extended Fund Facility (EFF) and $1.4 billion under the Resilience and Sustainability Facility (RSF), also supported the market recovery.
State Bank of Pakistan (SBP) reserves increased by 13pc to $11.5 billion by the end of May, primarily due to disbursements from the IMF.
Sectors that positively contributed to the index in May included banks, fertilizer, exploration and production (E&P), cement, and investment banks.Conversely,auto assemblers,tobacco,auto parts,synthetics,and vanaspati sectors showed negative contributions.
What’s next
The Federal Budget FY26 and the Monetary Policy Committee (MPC) meeting in June are key events that will likely influence market sentiment. With inflation moderating and real interest rates remaining high, market participants anticipate a potential rate cut, which could act as a tailwind for equities.