
Reassessing Interest Rates, Housing, and Macroeconomic Orthodoxy
- Mortgage rates and housing market trends face a new analytical framework following an analysis published by Kevin Erdmann on his Substack column.
- Economics remains in its adolescence regarding data collection and analysis on major questions, according to the analysis on kevinerdmann.substack.com.
- Rhetorical insistence from orthodox macroeconomists attributes long-term interest rate spikes to expectations of future Federal Reserve rate hikes.
Mortgage rates and housing market trends face a new analytical framework following an analysis published by Kevin Erdmann on his Substack column. In a column for kevinerdmann.substack.com, Kevin Erdmann argues that high interest rates are currently good news for the economy and the housing market rather than a traditional negative force, challenging orthodox macroeconomic presumptions about Federal Reserve policy.
Challenging Orthodoxy in Housing Markets and Economic Cycles
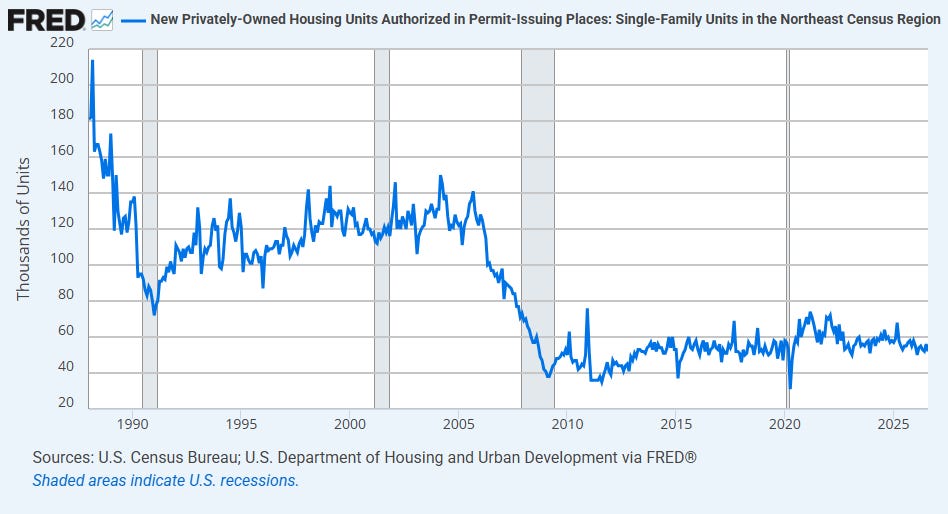
Economics remains in its adolescence regarding data collection and analysis on major questions, according to the analysis on kevinerdmann.substack.com. Erdmann contends that over a decade of building a heterodox case on housing shows that the last 30 years of American housing history do not support standard canons like superstar cities theories or pre-2008 supply gluts. The analysis points to a continuous post-2008 shift across a region spanning from Pittsburgh through Philadelphia, New York City, and Boston to Bangor. This geographic region fails to align with conventional narratives, prompting the need for alternative analytical frameworks to understand modern real estate markets.
Yield Curve Movements Challenge Federal Reserve Policy Assumptions
Rhetorical insistence from orthodox macroeconomists attributes long-term interest rate spikes to expectations of future Federal Reserve rate hikes. Erdmann asserts that yield curve movements since August push against that assumption. While Federal Reserve tightening offered a plausible reason for rate increases between August and September 23, subsequent market behavior diverged. Since September 23, the short end of the yield curve retreated while the long end continued to rise, suggesting that short-term interest rates associated with a 2% inflation trend have actually been climbing.
Data breakdowns of the 10-year Treasury yield reveal that all recent increases occurred on the real component rather than the inflationary component, reflecting a strong investment cycle and a bias toward risk-taking. Erdmann notes that since 2021, the real 10-year yield rose by 4 percentage points, while the inflation premium remained in a tight band near the official 2% target. Market monetarists, as referenced in the analysis, prefer removing interest rate targets from Federal Reserve communications because rate target language creates confusion compared to basic monetary activities like purchasing Treasuries.
Implications for Housing Supply and Economic Sentiment
High interest rates function primarily as a result of economic sentiment and risk tolerance rather than a pure cause of capital investment, according to the kevinerdmann.substack.com report. High yields prove bullish for housing because broader economic growth benefits the sector. While a clear negative correlation existed between new home sales and interest rates from the 1960s to the 1980s—when housing supply wasn’t throttled and Federal Reserve inflationary bias dictated business cycles—that specific relationship has remained largely irrelevant for the past 40 years.