
What Does a Finance Charge on a Mortgage Include? – 719 Lending
- The finance charge on a mortgage includes the total interest paid over the loan term plus prepaid loan charges such as origination fees, discount points, mortgage insurance, and...
- The finance charge represents the total cost of borrowing, combining interest payments and upfront lender fees.
- The finance charge appears on page 5 of the Closing Disclosure under the "Loan Calculations" section.
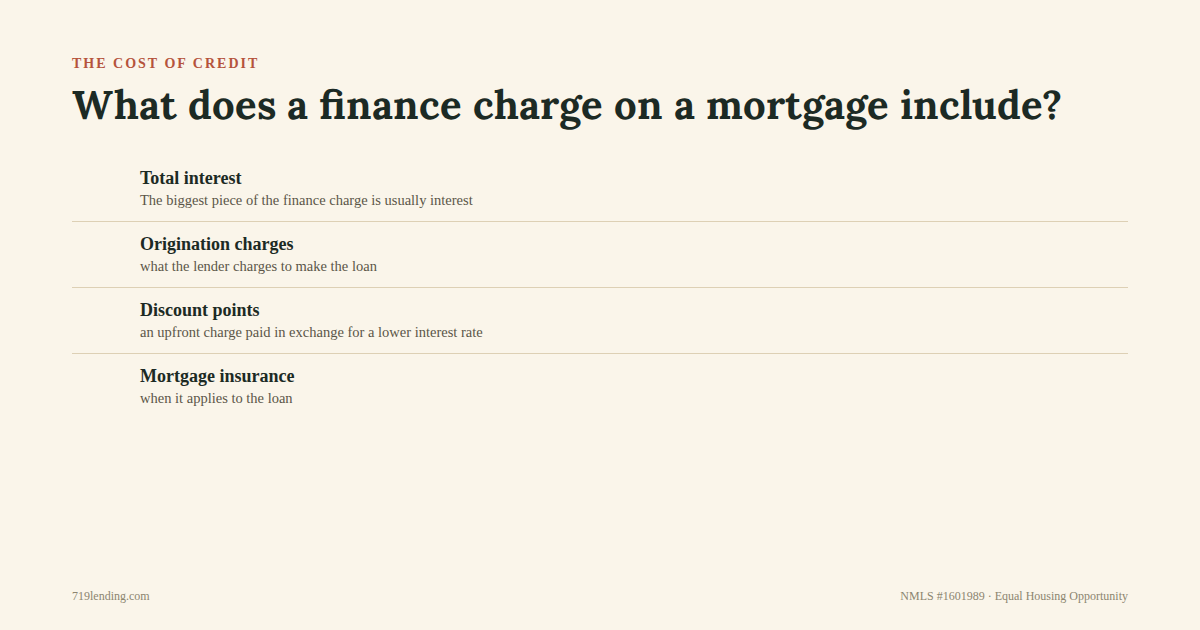
The finance charge on a mortgage includes the total interest paid over the loan term plus prepaid loan charges such as origination fees, discount points, mortgage insurance, and other lender fees, according to 719 Lending. This figure assumes the borrower keeps the loan until maturity and is listed on page 5 of the Closing Disclosure form.
What Is Included in a Mortgage Finance Charge?
The finance charge represents the total cost of borrowing, combining interest payments and upfront lender fees. The Consumer Financial Protection Bureau (CFPB) defines this as the “total amount of interest and loan charges” over the loan’s lifetime.
- Origination charges: Fees charged by the lender to process the loan.
- Discount points: Upfront fees paid to reduce the interest rate.
- Other lender charges: Additional fees tied to extending the loan.
Where to Find the Finance Charge in Mortgage Documents
The finance charge appears on page 5 of the Closing Disclosure under the “Loan Calculations” section. This form is the final document reviewed before closing, detailing all loan terms and costs. Earlier, borrowers receive a Loan Estimate, which provides a preliminary view of costs. The Closing Disclosure’s finance charge reflects the actual terms of the loan as it will close.
For loans that do not use a Closing Disclosure—such as reverse mortgages, home equity lines of credit (HELOCs), or certain manufactured home loans—the finance charge is outlined in Truth-in-Lending disclosures instead.
How the Finance Charge Differs From Closing Costs, Interest Rates, and APR
The finance charge is often confused with closing costs, but the two are distinct. Closing costs include third-party fees like appraisals, title insurance, and government taxes, while the finance charge focuses on the cost of credit itself. For instance, property taxes and recording fees are part of closing costs but not the finance charge.
The finance charge also differs from the interest rate and annual percentage rate (APR). The interest rate determines monthly payments, while the APR includes the interest rate and other fees, expressed as an annualized rate. The finance charge, however, is a total dollar amount reflecting all costs over the loan’s lifetime.
Who Pays the Finance Charge?
Borrowers typically pay finance charges directly, though sellers or lenders may indirectly cover some costs. For example, a seller might offer a credit to reduce closing costs, but this often results in a higher home price. Similarly, lenders may provide credits in exchange for a higher interest rate or increased loan amount, shifting costs into the finance charge.
How to Use the Finance Charge When Comparing Mortgages
The finance charge simplifies comparing loans by consolidating interest and fees into a single figure. For instance, two loans with similar monthly payments may have vastly different finance charges if one includes higher origination fees or a longer term. Borrowers should prioritize reviewing page 5 of the Closing Disclosure first and compare it with the Loan Estimate to identify discrepancies in government recording charges.
Key considerations include:
- Loan term: A longer term increases total interest, raising the finance charge.
- Credits: Ask whether seller or lender credits affect the loan amount, interest rate, or closing costs.
- Duration: The finance charge assumes the loan is held to maturity. Shorter stays, such as due to a military relocation, may make upfront fees less advantageous.
Frequently Asked Questions
What is included in a mortgage finance charge? It includes total interest over the loan term plus prepaid loan charges like origination fees, discount points, and mortgage insurance, assuming the loan is held to maturity.
Where do I find the finance charge on my mortgage documents? The finance charge is listed on page 5 of the Closing Disclosure in the “Loan Calculations” section. Loans like reverse mortgages use Truth-in-Lending disclosures instead.
Is the finance charge the same as closing costs? No. The finance charge focuses on the cost of credit (interest and lender fees), while closing costs include third-party and government fees like appraisals, title insurance, and recording charges.