
Why European Renewable Energy Business Models Are Failing
- The European electricity market has transformed far faster than the renewable business models built around it, triggering widespread financial stress across the continent's green energy sector.
- Enerparc's insolvency highlights deeper structural pressures facing renewable energy companies throughout Europe.
- Beyond Enerparc, other players in the German market—including BayWa, ABO Energy, PNE, and SOWITEC—have encountered financial stress.
The European electricity market has transformed far faster than the renewable business models built around it, triggering widespread financial stress across the continent’s green energy sector. Enerparc, a German solar developer and independent power producer, filed for insolvency proceedings in Germany, signaling systemic vulnerabilities in how renewable assets are financed and managed.
Enerparc Insolvency Exposes Deep-Seated Vulnerabilities
Financial Strain Spreads Across the German Market
Enerparc’s insolvency highlights deeper structural pressures facing renewable energy companies throughout Europe.
Beyond Enerparc, other players in the German market—including BayWa, ABO Energy, PNE, and SOWITEC—have encountered financial stress. This instability is not confined to Germany, as businesses stretching from Sweden to France and Spain face pressure.
Lagging Infrastructure and Unmet EU Targets
For two decades, European energy policy focused heavily on deploying massive volumes of renewable generation to meet European Union targets and national support schemes.
By 2025, renewables supplied approximately 50 percent of electricity consumed in the EU. However, infrastructure development failed to keep pace. Governments and markets built fewer grids, storage facilities, and commercial frameworks than necessary to handle a system dominated by weather-dependent generation.
Negative Pricing Cannibalizes Renewable Revenues
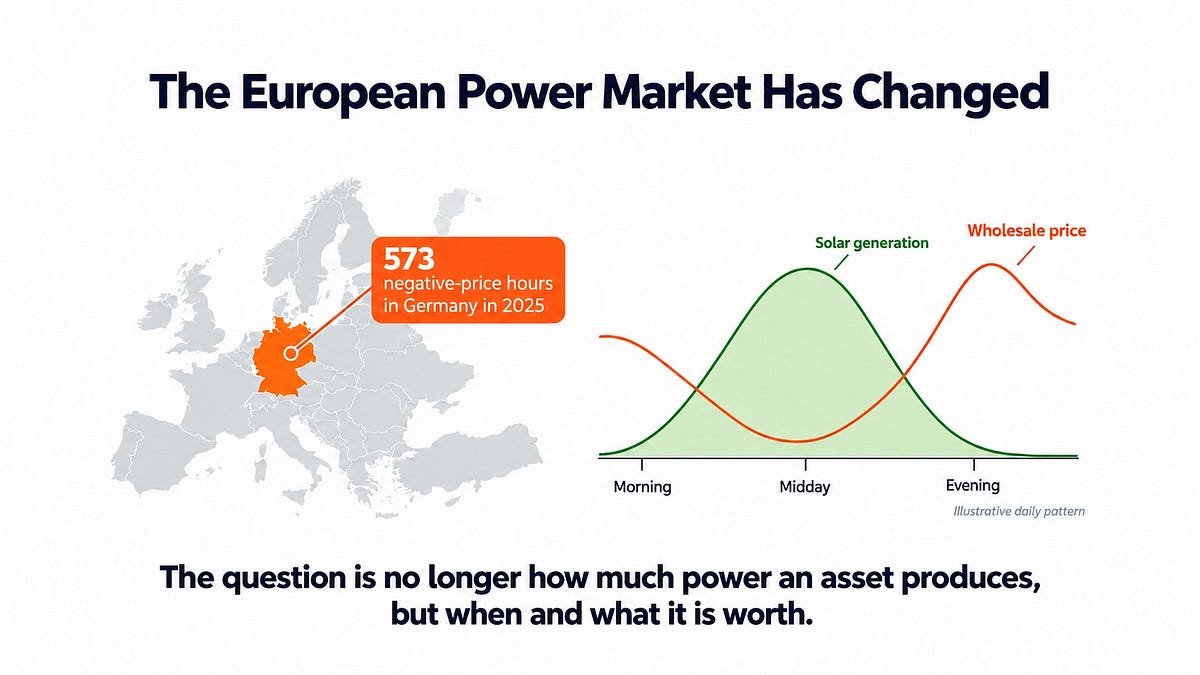
The resulting market features heightened volatility, grid congestion, and frequent negative pricing that cannibalizes renewable revenues.
In 2025, Germany recorded 573 hours of negative day-ahead electricity prices as wholesale rates dropped below zero, up from 457 hours in 2024. Solar generation heavily drives this trend: when the sun shines, power prices plummet, only to rebound sharply a few hours later.
Limitations of Traditional Asset Management
This volatility exposes the limitations of traditional asset management approaches.
Historically, managing renewable assets functioned primarily as an engineering exercise supported by feed-in tariffs, subsidy regimes, and long-term power purchase agreements. The core objective was maximizing production while keeping operating expenses low.
Outdated Financial Structures and Yield Compression
Renewable business models heavily relied on yield compression, treating power plants as financial products rather than dynamic energy assets. Early-stage developers sold projects to late-stage developers for construction, who then passed them to independent power producers. These producers aggregated operating portfolios and eventually sold them to low-cost capital providers like pension funds seeking predictable, low-risk returns.
Each transaction step compressed required yields while depending on stable cash flows. The underlying solar parks and wind turbines remain operational and productive, but the commercial structures and revenue assumptions surrounding them were built for a different regulatory and economic era. With volatile pricing and falling capture values, traditional renewable business models face more risk around investing in the European renewables market than ever before.